Ohio politicians are treating the data-center boom as though the state faces a binary choice.
Embrace AI, data centers and billions of dollars of promised investment.
Or stand in the way of progress.
There is a third choice:
Audit the deals.
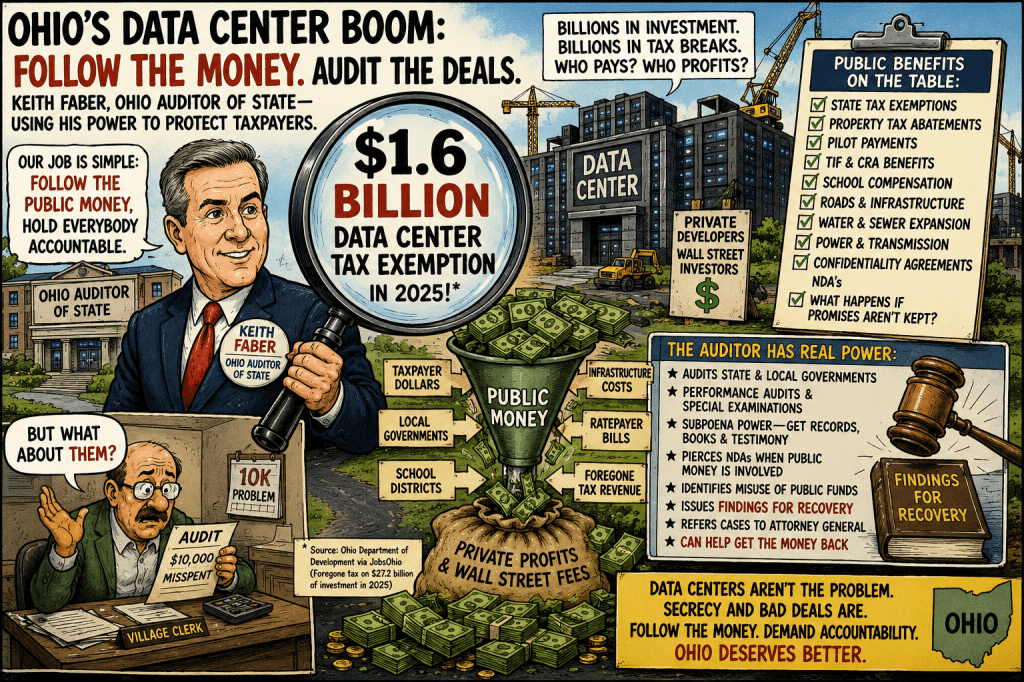
Ohio already has an independently elected official with extensive authority to audit state and local government, investigate misuse of public money and issue findings for recovery when public funds have been misspent.
His name is Keith Faber, Ohio Auditor of State.
And the extraordinary amount of public money now intertwined with Ohio’s data-center boom makes this an obvious subject for aggressive public auditing.
The Auditor doesn’t need to decide whether AI is good.
He doesn’t need to decide whether data centers are bad.
He doesn’t need to become Ohio’s zoning board or utility regulator.
He needs to do something much simpler:
Follow the public money.
Start With $1.6 Billion
Ohio’s data-center boom is not simply a private-sector construction boom.
Ohio’s own economic-development materials say the state’s Data Center Tax Exemption can exempt eligible equipment from state, county and transit sales and use taxes.
According to JobsOhio’s 2026 data-center guide, the Ohio Department of Development reported approximately $555 million in foregone tax on $9.6 billion of capital investment in 2024.
Then look at 2025:
Approximately $1.6 billion in foregone tax on $27.2 billion of investment.
That is an enormous amount of foregone public revenue.
Call it an exemption rather than an expenditure if you want.
But from the taxpayer’s perspective, the fundamental question is the same:
What did Ohio give up, and what did Ohio get in return?
That is an audit question.
Faber Has Already Asked Exactly That Question
This isn’t some radical expansion of the Auditor’s role.
Keith Faber’s office is already auditing economic-development incentive compliance.
In December 2025, the Auditor reported that a majority of companies examined that had received state loans or tax credits had failed to meet job-creation and/or payroll commitments.
Thirty-nine of 60 companies with job-creation commitments were listed as noncompliant.
Even more troubling, the Auditor found that no action had been taken against many companies deemed noncompliant with economic-incentive agreements since 2021.
Faber’s response was exactly right.
If Ohio isn’t going to hold companies accountable for their commitments, then the agreements simply deprive Ohioans of financial resources that could have been used elsewhere.
Now apply that same philosophy to data centers.
Audit the Data-Center Bargain
Data centers are particularly appropriate for performance auditing because the public-policy bargain is unusually complicated.
The headline number is always enormous:
$1 billion investment.
$5 billion investment.
$10 billion investment.
But investment isn’t the same thing as public benefit.
How many permanent jobs are created?
What are their salaries?
How much tax revenue is actually generated?
How much tax revenue is surrendered?
How much public infrastructure is required?
Who pays for roads?
Who pays for water?
Who pays for sewer expansion?
Who pays for transmission?
Who pays for electric generation?
What happens if projected investment never occurs?
What happens if ownership changes?
What happens if the data center closes?
Those aren’t anti-business questions.
They are the questions anyone investing his own money would ask.
Ohio taxpayers deserve the same due diligence.
Ohio’s Local Deals Are Even More Complicated
The state tax exemption is only the beginning.
Ohio’s own data-center economic-development materials describe an entire menu of local arrangements.
Communities can use Community Reinvestment Areas to provide property-tax abatements.
They can establish Enterprise Zones.
They can use Tax Increment Financing.
They can negotiate PILOTs—payments in lieu of taxes.
They can enter development agreements and host-community agreements involving infrastructure costs, roads and other obligations.
And school districts can become part of the negotiations because property-tax abatements directly affect the tax base supporting public education.
That means a supposedly private data-center project can quickly become an extraordinarily complicated web of:
state tax exemptions + local property-tax abatements + PILOTs + TIFs + school compensation + roads + water + sewer + electric infrastructure + development agreements.
That is exactly the kind of financial complexity in which public obligations can disappear from public view.
Follow the Schools
Ohio’s own data-center guide identifies school compensation as a central issue.
Why?
Because when a local government abates property taxes, schools can lose the tax revenue they otherwise would have received.
Ohio communities have attempted to compensate for that through individually negotiated arrangements.
Sidney reportedly directs part of its PILOT revenue toward schools.
Marysville uses specified annual payments.
Piqua uses another formula involving land value and payments for individual data-center buildings.
That’s three different approaches to essentially the same problem.
The Auditor should ask:
Which approach actually protects taxpayers and schools?
Create a statewide database.
For every major data-center project, calculate:
property taxes otherwise payable;
property taxes abated;
PILOT payments;
school compensation;
infrastructure expenditures;
permanent employment;
payroll;
and the net financial impact on the community.
Then let Ohio citizens compare the deals.
Follow the Water
Data centers can consume enormous amounts of water.
But the relevant Auditor question isn’t whether water consumption is environmentally good or bad.
It is:
Who paid for the infrastructure?
Did the municipality expand its water system?
Did it issue debt?
Did ordinary customers finance capacity primarily needed by the data center?
Was the developer charged the full incremental cost?
Were special water rates negotiated?
What happens if projected consumption changes?
Were taxpayers effectively financing infrastructure for a private developer?
That is public finance.
Audit it.
Follow the Electricity
The Auditor doesn’t set electric rates.
PUCO does.
But that doesn’t mean the Auditor should ignore public financial decisions connected to electric infrastructure.
Ohio’s exploding data-center demand could require enormous amounts of generation and transmission.
Someone will pay for it.
The appropriate public-accountability question is whether costs attributable to enormous private industrial users are being shifted toward ordinary Ohio families, schools, municipalities or other ratepayers.
Where state agencies, municipalities, counties or other auditable public entities participate financially, the Auditor should follow those dollars.
Follow the NDAs
Data-center negotiations frequently involve confidentiality.
Some confidentiality may be legitimate.
A company can have real trade secrets and commercially sensitive information.
But commercial confidentiality should never become a mechanism for hiding public financial obligations from public oversight.
Ohio’s own 2026 data-center negotiation guide recognizes “confidentiality and public records handling” as one of the negotiable issues in these transactions.
That alone should get the Auditor’s attention.
An NDA signed by a mayor, development official or other public entity shouldn’t be treated as a magic curtain behind which public financial obligations disappear.
The Auditor should examine every confidentiality provision connected with a major publicly assisted data-center project and determine whether it interfered with appropriate governmental oversight or concealed material public obligations.
And Ohio’s Auditor Has Real Investigative Muscle
The Auditor of State isn’t a newspaper columnist filing records requests.
The office audits thousands of Ohio state and local government agencies.
Ohio law gives the Auditor substantial authority to obtain information necessary to conduct audits.
And the office has a Special Investigations Unit specifically devoted to suspected fraud and misuse of public resources.
That unit doesn’t merely issue reports.
Its investigations can lead to criminal referrals, restitution and findings for recovery.
That last phrase is important.
Ohio Has Something Particularly Powerful: Findings for Recovery
Ohio’s system goes beyond embarrassing an official in an audit report.
When public money has been illegally expended or public property has been misappropriated, the Auditor can issue a finding for recovery.
And there are consequences.
The public office’s legal counsel is authorized to pursue collection.
The Auditor notifies the Ohio Attorney General.
If appropriate legal action isn’t initiated within the statutory period, the Attorney General can pursue recovery.
An unresolved finding can also prevent a person or business from receiving certain public contracts.
Think about how dramatically that changes the accountability equation.
A bad data-center deal isn’t merely:
“The Auditor thinks taxpayers got a bad bargain.”
If an examination uncovers actual unlawful expenditures or recoverable public money, Ohio has a mechanism for identifying the money and pursuing its return.
The Auditor isn’t simply a critic.
He can help create the financial record upon which recovery occurs.
Faber Has Already Demonstrated the Model
Ohio doesn’t have to invent a hypothetical Auditor’s Office capable of doing this.
Faber’s Special Investigations Unit regularly conducts special audits of villages, schools, townships and other public entities.
Those investigations have produced findings for recovery involving unauthorized compensation, improper expenditures and misuse of public resources.
In other words:
The machinery already exists.
The question is whether Ohio will deploy that machinery against transactions measured in billions rather than merely thousands.
That is where this becomes interesting.
Don’t Just Audit the Little Guy
Auditors naturally catch fiscal officers who steal money.
They catch employees receiving improper compensation.
They identify credit-card abuse.
Good.
Keep doing it.
But consider the scale.
A $25,000 theft from a village matters.
So does a $100,000 improper payment.
But Ohio reported approximately $1.6 billion of foregone data-center taxes in a single year.
If the Auditor’s job is protecting public money, the largest financial transactions deserve at least as much scrutiny as the smallest.
The potential public exposure from a single poorly negotiated data-center agreement could dwarf dozens of ordinary findings for recovery.
Audit the Promises
Every publicly assisted data-center deal should receive a standardized performance audit.
The Auditor should compare:
Promised capital investment vs. actual investment.
Promised jobs vs. actual jobs.
Promised payroll vs. actual payroll.
Taxes theoretically generated vs. taxes actually collected.
Taxes theoretically owed vs. taxes abated.
Developer infrastructure commitments vs. taxpayer infrastructure costs.
School revenue lost vs. compensation received.
Projected water demand vs. actual water demand.
Projected public costs vs. actual public costs.
And perhaps most importantly:
Who bears the risk if the projections are wrong?
That last question is routinely ignored during economic-development celebrations.
Follow the Wall Street Money Too
This is where the data-center audit connects with the larger CommonSense story about Ohio pensions.
Ohio teachers contribute money to STRS.
STRS invests billions through public securities, private equity, private credit, real estate and infrastructure.
Many of the largest private-market managers are simultaneously financing the enormous AI and data-center buildout.
Carlyle says it manages approximately $1.5 billion for Ohio state teachers and public employees while Carlyle-backed Ark Data Centers has been expanding in Ohio.
STRS has a direct lending relationship through Blue Owl Credit SLF while Blue Owl has become a major digital-infrastructure investor.
Blackstone, Apollo and KKR-managed vehicles have participated in enormous power-generation investments that include Ohio projects.
STRS also has enormous public-equity exposure to Nvidia, Microsoft, Amazon, Meta and other companies driving AI computing demand.
That does not prove STRS money financed any particular Ohio data center.
It proves the opposite point:
Ohio’s financial relationships have become too complicated to rely upon labels.
Ohio needs look-through transparency.
Now Put Vivek Ramaswamy Into the Picture
That transparency becomes even more important as Ohio chooses its next governor.
Vivek Ramaswamy’s financial interests and political agenda intersect with technology, cryptocurrency and the broader digital economy.
A governor would influence an administration making decisions involving economic development, tax policy and appointments affecting infrastructure and utility regulation.
That doesn’t mean a governor personally approves every pension investment or data-center agreement.
It means Ohio needs institutional checks that don’t depend upon who occupies the governor’s office.
An independently elected Auditor is one of those checks.
Whether the governor is Republican or Democrat shouldn’t matter.
Whether the data-center developer is politically connected shouldn’t matter.
Whether the private-equity firm has billions invested in Ohio shouldn’t matter.
Follow the money anyway.
Create an Ohio Data Center Accountability Audit
Keith Faber could create an Ohio Data Center Accountability Audit covering every major project receiving material state or local public assistance.
For every project, the Auditor should identify:
- State sales-and-use tax exemptions.
- Local property-tax abatements.
- CRA and Enterprise Zone benefits.
- TIF arrangements.
- PILOT agreements.
- School compensation agreements.
- Publicly financed roads and infrastructure.
- Water and wastewater commitments.
- Public debt issued in connection with the development.
- Confidentiality and nondisclosure agreements involving public entities.
- Promised and actual jobs and payroll.
- Promised and actual capital investment.
- Ownership changes and assignments.
- Public financial guarantees and contingent liabilities.
- Potential conflicts involving officials, consultants and counterparties.
- Compliance with every material promise used to justify public assistance.
Then put it online.
Not 200 pages of government accounting jargon.
Build a searchable database.
Data Center. Developer. Owner. Tax Break. Local Subsidy. Jobs Promised. Jobs Delivered. Public Infrastructure Cost. School Impact. Water Commitment. Compliance Status.
Let taxpayers see the deal.
Ohio’s Auditor Could Become the Most Important Data-Center Regulator Who Isn’t a Regulator
Keith Faber cannot decide where every data center gets built.
He doesn’t regulate electric rates.
He doesn’t issue every zoning permit.
He doesn’t run STRS.
That’s precisely the point.
The Auditor doesn’t need to take over anybody else’s job.
He can do his own.
Audit the public money.
Ohio’s data-center boom is becoming one of the largest transfers and reallocations of economic resources in the state’s recent history.
Private companies are investing tens of billions.
Government is foregoing enormous amounts of tax revenue.
Local governments are negotiating abatements.
Schools are negotiating compensation.
Communities are confronting infrastructure costs.
Utilities are preparing for enormous new electric demand.
Wall Street is financing the boom.
And Ohio pension money may be invested throughout the same financial ecosystem.
There may be excellent deals among them.
There may be terrible deals.
There may be perfectly legal deals that simply represent lousy economics for taxpayers.
And there may eventually be transactions involving improper expenditures or public money that should be recovered.
We shouldn’t have to guess.
Follow the Money
Ohio already has an independently elected Auditor.
He already audits state and local government.
His office already investigates misuse of public money.
It already audits compliance with economic-development incentives.
It already issues findings for recovery.
And Faber himself has already complained that Ohio has failed to hold companies accountable when they don’t deliver the jobs and payroll they promised in exchange for economic-development assistance.
So apply the same standard to the biggest economic-development boom in Ohio.
Don’t just audit the village clerk who misspent $10,000.
Audit the billion-dollar data-center tax breaks.
Audit the PILOTs.
Audit the TIFs.
Audit the infrastructure.
Audit the school agreements.
Audit the promises.
Audit the NDAs where public entities are involved.
And where public money was illegally spent, identify it and pursue the mechanisms Ohio law provides for recovery.
Ohio doesn’t need an Auditor who decides whether artificial intelligence is good or bad.
It needs an Auditor willing to ask the question every Ohio taxpayer has a right to ask:
Where did our money go—and did we get what we paid for?
 The CommonSense 401k Project

Pingback: Ohio’s Data-Center Money Machine: Husted, Ramaswamy, Faber, SFOF and Wall Street | The CommonSense 401k Project