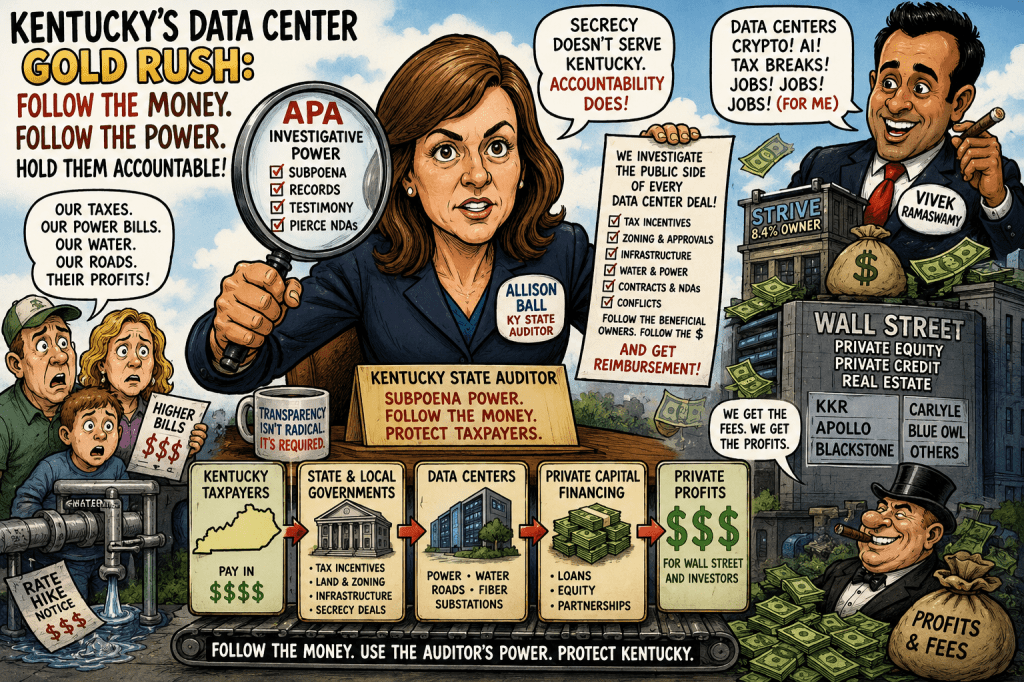
Kentucky politicians keep talking about data centers as though citizens have only two choices:
Approve them. Or complain about them. There is another option sitting in Frankfort.
Audit them.
Kentucky’s Auditor of Public Accounts may possess one of the most powerful—and so far underappreciated—tools for bringing transparency to Kentucky’s data-center gold rush.
The Auditor cannot simply prohibit a privately financed data center because she doesn’t like the project. She isn’t the Public Service Commission, a zoning board or the General Assembly.
But that isn’t where the most interesting power lies.
Data centers increasingly depend upon an enormous web of public decisions and public resources:
tax incentives; local-government agreements; zoning and development decisions; public infrastructure; roads; water and sewer capacity; economic-development arrangements; utility infrastructure; and potentially hundreds of millions or billions of dollars of commitments whose ultimate costs can migrate toward taxpayers and ratepayers.
Where public money and public agencies enter the transaction, the Kentucky Auditor can enter the picture too. And unlike an ordinary citizen filing an Open Records request, the Auditor has statutory investigative powers.
The Auditor Can Follow the Public Money
The Kentucky Auditor describes the office as an independent constitutional office charged with auditing public funds.
Its jurisdiction includes state agencies, fiscal courts and other public or quasi-public entities receiving government funds.
More importantly, the APA isn’t limited to checking whether columns on a financial statement add correctly. It conducts performance audits and special examinations.
That creates an obvious data-center application. The relevant question isn’t:
Should Kentucky have data centers?
The audit question is:
What did Kentucky taxpayers give away, what obligations did government assume, who made those decisions, what information did they rely upon, and did taxpayers receive value in return?
Those are classic public-accountability questions.
The Auditor Has Something Reporters and Citizens Don’t: Compulsory Investigative Power
This is where things get interesting. KRS Chapter 43 gives the Auditor access to books and records and authority to obtain testimony.
That changes the balance of power. A reporter can ask. A citizen can file an Open Records request. A county resident can stand up at a fiscal-court meeting.
The Auditor can conduct an examination using statutory authority. That potentially makes the APA one of Kentucky’s best tools for following the money through a data-center transaction.
What About the NDAs?
This may be the biggest issue of all.
Data-center developers have increasingly relied upon nondisclosure agreements and claims of commercial confidentiality while negotiating with public officials.
An NDA may frustrate a citizen. It should not automatically defeat the statutory oversight authority of the Commonwealth’s Auditor.
Kentucky’s own procurement regulations illustrate the principle. State contracts must provide governmental oversight agencies—including the Auditor—with access to books, documents, papers, records and other evidence directly pertinent to the contract for purposes of financial audit or program review.
In other words:
Government cannot simply privatize public accountability by signing a confidentiality agreement.
There may still be legitimately protected trade secrets and confidential information, and the Auditor herself operates under confidentiality requirements governing information obtained during examinations.
But that is very different from saying the Auditor cannot examine the material.
In fact, the APA’s ability to receive confidential information while protecting it may make the Auditor particularly well suited to examine data-center deals.
Kentucky Legislators Have Already Identified the NDA Problem
This isn’t theoretical. Kentucky Senate Bill 330 was introduced in 2026 specifically to address data-center secrecy.
The proposal would prohibit public agencies from entering data-center confidentiality agreements that expand secrecy beyond what Kentucky law permits. It would also declare certain contractual provisions attempting to override Kentucky’s Open Records and Open Meetings laws void.
Why was such legislation proposed? Because secrecy surrounding data-center negotiations has become a public-policy problem. But Kentucky doesn’t necessarily have to wait for another legislative session to begin examining deals that already involve public money.
The Auditor has an existing oversight infrastructure.
Use it.
Audit the Zoning Process—Not the Zoning Decision
There is an important distinction here. The Auditor probably cannot tell a city or county:
You may not zone this property for a data center.
But the Auditor can potentially examine the financial transactions, controls, procedures and public expenditures surrounding local government.
That could include questions such as:
Were required procedures followed?
Were public resources committed before proper authorization?
Were economic assumptions independently verified?
Were officials given information that the public never saw?
Did consultants have conflicts?
Were infrastructure costs accurately presented?
Were taxpayer obligations omitted from the public discussion?
Did officials negotiate concessions that transferred costs from the developer to the public?
Did the government properly value land, infrastructure or other benefits provided to the project?
Were public funds used economically and for authorized purposes?
That isn’t second-guessing zoning.
That’s auditing government.
And a serious audit conducted while a controversial project is developing could dramatically change the political and financial environment surrounding it.
Follow the Water
A data center can require enormous water infrastructure.
So audit it.
Who pays for additional capacity?
Who pays for pipes?
Who finances treatment facilities?
Were preferential rates negotiated?
Are ordinary customers subsidizing the development?
What happens if projected demand doesn’t materialize?
What guarantees did the developer provide?
Kentucky citizens shouldn’t discover ten years later that a supposedly private development produced a public infrastructure liability.
Follow the Electricity
The Auditor doesn’t regulate electric rates.
But government involvement surrounding electric infrastructure and economic development can still create auditable public transactions.
What incentives were offered?
What infrastructure commitments were made?
Were economic-development assumptions reasonable?
Did government entities properly analyze contingent liabilities?
Were costs shifted elsewhere?
And were public officials simultaneously being told one story publicly and another story under NDA?
The Auditor can follow the public-dollar trail even when another regulator has jurisdiction over electricity itself.
Follow the Tax Breaks
This may be the easiest place to start.
Kentucky’s data-center strategy is built partly upon tax incentives.
Tax incentives aren’t magic money.
They represent public policy deliberately foregoing revenue in exchange for promised economic benefits.
That makes performance an obvious question:
What did taxpayers give up and what did taxpayers receive?
An Auditor’s performance examination could compare:
projected employment versus actual employment;
projected capital investment versus actual investment;
promised tax revenue versus foregone revenue;
developer-paid infrastructure versus taxpayer-funded infrastructure;
projected electricity and water consumption versus actual consumption;
and economic-development claims versus independently measurable results.
Instead of debating whether a project “creates jobs,” put the numbers on a spreadsheet.
And Follow the Politicians
This brings the Auditor directly into the issues I raised in my earlier pieces about Kentucky’s data-center boom and the relationships among politicians, pension money and enormous private-market investment managers.
Public officials shouldn’t be able to hide public financial decisions behind slogans like “economic development.”
Who proposed the incentive?
Who negotiated it?
Who reviewed it?
What outside consultants participated?
Who represented the developer?
What investment managers ultimately own or finance the project?
What political contributions or other relationships exist?
Did Kentucky pension systems have investments with the same financial firms appearing elsewhere in the transaction?
None of those facts automatically establishes wrongdoing.
They establish the need for transparency.
Allison Ball Is in an Especially Interesting Position
That makes State Auditor Allison Ball’s position fascinating.
Ball has cultivated a national political profile through the State Financial Officers Foundation and attacks on ESG.
But the data-center boom provides an unusually concrete test of what financial accountability actually means.
Forget ESG rhetoric for a moment.
Here is a straightforward taxpayer question:
Will Kentucky’s Auditor use the powers of her office to examine whether giant data-center developers and their Wall Street financiers are receiving sweetheart arrangements from Kentucky governments?
If the answer is yes, that could put Ball in conflict with powerful economic-development interests, utilities, developers, private-equity firms and potentially members of her own party.
That is precisely why an independently elected Auditor exists.
The Auditor Could Create a Kentucky Data Center Audit Program
The APA doesn’t need to investigate whether artificial intelligence is good or bad.
It could establish a narrowly financial Kentucky Data Center Accountability Initiative examining projects receiving significant state or local government assistance.
The mandate could be simple:
Follow every public dollar.
For each major project, identify:
- State and local tax incentives.
- Public land or property concessions.
- Roads and transportation expenditures.
- Water and sewer commitments.
- Public infrastructure obligations.
- Economic-development grants.
- Contracts and side agreements.
- Confidentiality agreements involving public entities.
- Consultants and professional fees.
- Promised versus actual employment.
- Promised versus actual investment.
- Contingent taxpayer liabilities.
- Conflicts involving public officials, consultants and counterparties.
- The ultimate owners and financiers benefiting from public assistance.
Then publish the results.
And Where Public Money Was Improperly Spent, Seek Recovery
The ultimate purpose shouldn’t merely be producing another government report.
Where an examination identifies unauthorized expenditures, overpayments, unsupported reimbursements or other improper uses of public money, the findings can become the basis for government recovery efforts or referrals to officials with authority to pursue repayment.
That distinction matters.
The Auditor isn’t a court awarding damages.
But an audit can identify who owes the taxpayers money and why.
That can be much more frightening to a politically connected developer than another angry speech.
Imagine What One Serious Audit Could Do
Imagine a controversial Kentucky data-center project approaching final approval.
The public is told the deal is confidential.
The developer cites an NDA.
Local officials say they cannot discuss negotiations.
Nobody can determine the real infrastructure cost.
Nobody knows exactly what taxpayers are providing.
Then the Auditor announces a special examination.
The APA obtains the agreements.
It examines the public expenditures.
It reviews the government’s assumptions.
It obtains testimony.
It traces the incentives.
It calculates the taxpayer exposure.
And it publishes everything the law permits it to publish.
Suddenly the economics of secrecy change.
That alone could have a chilling effect on bad deals.
Not because the Auditor banned data centers.
Because she made politicians and developers show their work.
Kentucky Doesn’t Need Another Data-Center Regulator. It Needs an Auditor Willing to Audit.
Kentucky already has zoning boards.
It already has utility regulators.
It already has economic-development agencies.
What it desperately needs is someone asking a different question:
Who is protecting the taxpayer?
The Kentucky Auditor of Public Accounts already possesses significant investigative authority over public money.
The office can conduct special examinations and performance audits.
It can obtain records.
It can obtain testimony.
It can examine local government.
And government confidentiality agreements do not magically erase statutory public oversight.
That creates an enormously powerful accountability mechanism.
Data-center developers may have billions of dollars.
Private-equity firms may have armies of lawyers.
Utilities may have lobbyists.
Politicians may have campaign contributions.
But Kentucky taxpayers have something too:
An independently elected Auditor with investigative powers.
The question isn’t whether Kentucky needs another law before anyone can investigate the data-center gold rush.
The better question may be:
Why isn’t the Auditor investigating it already?
One legal nuance I would preserve: “pierce the NDA” is excellent shorthand for the article, but legally I would say an NDA generally cannot be assumed to defeat APA’s independent statutory access rights. The Auditor also has confidentiality rules protecting material obtained during an examination, which strengthens the argument that commercially sensitive material can be examined without necessarily being indiscriminately released.
There’s another very useful fact: SB 330 is sitting in Committee on Committees as of the legislature’s August 19 update. Its text would specifically prevent data-center NDAs from expanding confidentiality beyond Kentucky law and would void contractual attempts to supersede Open Records/Open Meetings requirements. That lets you contrast the legislature considering future transparency legislation with APA possessing significant investigative authority right now.
I would next dig into KRS 43.080 and 43.090 and prior APA special examinations where the Auditor compelled records/testimony and recommended or triggered recovery of public money. That could turn this from an opinion piece into a very specific blueprint for an APA data-center investigation.
https://commonsense401kproject.com/2026/08/22/kentuckys-data-center-election-follow-the-money-follow-the-power-and-hold-the-republicans-accountable/ https://commonsense401kproject.com/2026/08/18/allison-balls-esg-shell-game-follow-the-money-from-kentucky-to-kkr-to-sfof/
 The CommonSense 401k Project

Pingback: Kentucky Auditor Allison Ball Supports Data Centers by Not Auditing Them—and Pushing Pensions Toward Them | The CommonSense 401k Project