Warren and Sanders demand answers from Trump’s Labor Department about fake support for private equity, private credit and cryptocurrency
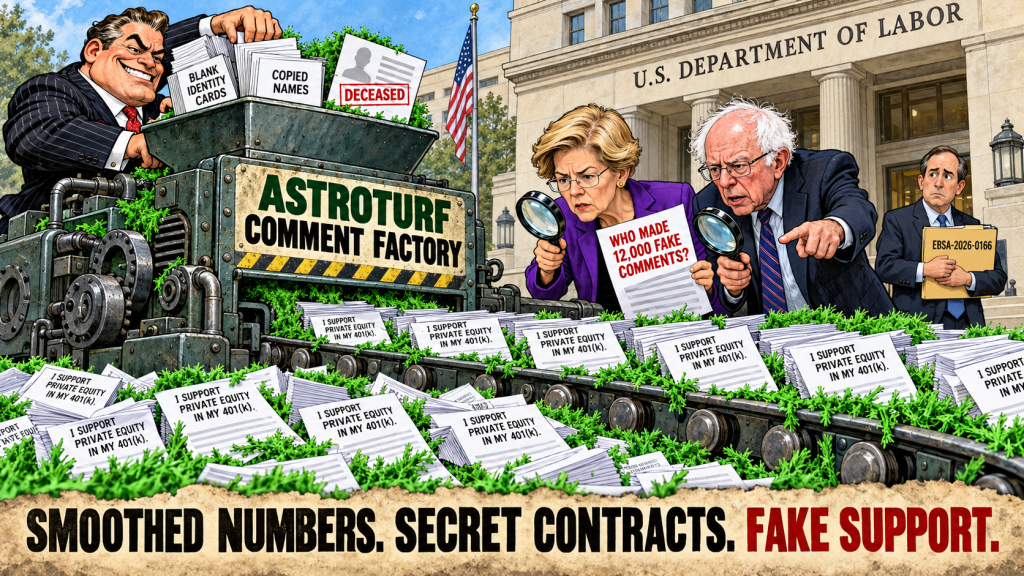
On September 25, Senators Elizabeth Warren and Bernie Sanders sent the Department of Labor a letter containing a question that should stop its proposed alternative-assets rule in its tracks:
Who manufactured nearly 12,000 public comments supporting the effort to open workers’ 401(k) accounts to private equity, private credit, cryptocurrency and other alternative assets?
The comments were supposed to demonstrate grassroots enthusiasm for putting Wall Street’s most opaque, illiquid and expensive products into ordinary retirement plans.
Instead, Bloomberg found five nearly identical templates submitted in similar daily quantities over roughly one week. The supportive comments lacked signatures and meaningful personalization. People whose names appeared on them said they had not submitted them. At least one purported commenter had reportedly been dead for approximately five months.
That is not grassroots support.
It is astroturf—with retirement money at stake.
And the senators’ letter raises an even more disturbing possibility: the Labor Department may have procedures that allow comments submitted under stolen or misused identities to remain in the rulemaking record.
DOL has until October 8 to explain itself
Warren, the ranking member of the Senate Banking Committee, and Sanders, the ranking member of the Senate HELP Committee, directed their questions to Acting Labor Secretary Keith Sonderling and EBSA Assistant Secretary Daniel Aronowitz. They requested answers by October 8, 2026.
Their questions go well beyond asking whether a few names were inaccurate. They ask DOL to disclose:
- its current guidance for comments containing potentially false identity information;
- whether that guidance has changed since 2019;
- whether identity-misused comments are merely relabeled as anonymous and left online;
- whether DOL is investigating Bloomberg’s findings;
- whether the investigation is attempting to identify the individual, company, organization or other entity that submitted or coordinated the comments;
- what submission metadata—including IP-address information—DOL retains and reviews;
- what controls detect mass submissions under different names; and
- whether DOL will authenticate the suspect comments before relying on them or claiming public support for the rule.
Those are exactly the right questions.
But DOL should answer one more:
Will it suspend this rulemaking until it can establish the integrity of the administrative record?
The most alarming part may be DOL’s existing policy
The Warren–Sanders letter points to a 2019 Government Accountability Office review of federal comment procedures. According to GAO, DOL guidance said that when someone falsely claims to be a commenter, the identifying information is removed, the comment is treated as anonymous—and the comment remains posted.
GAO also found that DOL’s guidance did not explain how officials determine that a submission used false identity information.
Think about what that means in this docket.
If someone borrowed thousands of names to manufacture support for Wall Street’s preferred rule, DOL’s apparent response might be to erase the names but preserve the manufactured advocacy as anonymous public opinion.
That would solve the identity problem by protecting the fake campaign instead of protecting the people whose identities were misused.
The Administrative Procedure Act may not require agencies to authenticate every commenter. But no serious rulemaking process should treat 12,000 coordinated, possibly unauthorized submissions as equivalent to 12,000 independent expressions of public support.
A template repeated 12,000 times is not 12,000 analyses.
And a stolen name is not a vote.
This is not DOL’s first fake-comment warning
The letter reminds DOL that the problem is not new.
In 2017, The Wall Street Journal examined comments concerning DOL’s earlier fiduciary rule. Forty percent of the individuals contacted reportedly said they had not written the comments attributed to them. Most of the 345 comments examined criticized the fiduciary rule and aligned with Wall Street’s policy position.
GAO later examined public-comment data that included EBSA submissions and estimated that between 5% and 30% of presumed commenters may not have submitted the comments attributed to them.
DOL therefore cannot credibly say it had no warning that its electronic comment system was vulnerable to identity misuse and coordinated flooding.
It was warned.
The same agency is now considering a rule that could channel trillions of dollars of defined-contribution assets toward industries desperate for new capital.
Follow the money, not the fake names
The proposed rule would establish a safe harbor for fiduciaries selecting investments containing private equity, private credit, digital assets and other alternatives.
The industries benefiting from that rule have an obvious economic interest in portraying it as a popular democratization of investments once reserved for wealthy institutions.
But the authentic comment record points in the other direction. According to the senators, more than 30,000 opposing comments generally included identifying details such as a city, state or email address. The nearly 12,000 suspect supportive comments lacked comparable personalization.
That does not prove which person or organization created them. It does establish why DOL must preserve and examine the electronic evidence before finalizing anything.
The investigation should follow:
- IP addresses and submission timestamps;
- browser, device and platform metadata retained by Regulations.gov or DOL;
- identical formatting, typographical artifacts and template variants;
- referral links and campaign landing pages;
- vendors or consultants that generated or transmitted the submissions;
- payments by asset managers, insurers, crypto interests, trade associations or advocacy groups;
- communications involving DOL, White House or industry personnel; and
- whether anyone presented the manufactured volume to policymakers as proof of genuine public support.
The relevant question is not merely whose names appeared on the comments.
It is who paid for the campaign, who executed it, who knew about it and whether anyone inside government relied on it.
The sales pitch being amplified was already misleading
The suspect comments did not arise in a vacuum. They supported an industry campaign built around claims that alternative assets will democratize opportunity, improve returns and diversify retirement portfolios.
But, as CommonSense previously explained in “Private Equity’s New 401(k) Sales Pitch: Fake Diversification From Smoothed Numbers”, much of private equity’s reported diversification advantage can be an artifact of valuation.
Public stocks confess their volatility every trading day. Private funds report valuations periodically, often using manager models and stale inputs. That can produce:
Smoothed NAV → lower reported volatility → lower reported correlation → higher reported Sharpe ratio → apparent diversification.
The economic risk did not necessarily disappear.
The ruler changed.
If thousands of manufactured comments were used to amplify a sales pitch already dependent on smoothed numbers, DOL faces two different integrity problems:
- Were the commenters authentic?
- Were the investment claims authentic?
A prudent fiduciary must demand unsmoothed volatility, stress-period correlations, secondary-market discounts and appropriate liquid comparators before accepting the claim that private equity reduces target-date-fund risk.
The contracts tell a different story from the marketing
CommonSense also reviewed actual private-equity limited-partnership agreements in “The Contracts Private Equity Doesn’t Want 401(k) Participants to See”.
Those agreements reveal an industry that understands ERISA extremely well—and drafts elaborate machinery to keep ERISA from following plan money into underlying fund assets.
The contracts use venture-capital-operating-company exceptions, benefit-plan-investor thresholds, feeder funds, parallel vehicles, alternative investment vehicles, conduit entities and other structures. They disclose potential monitoring, transaction, advisory, financing, breakup, director and affiliated fees. They include transfer restrictions, manager-controlled valuations, indemnification provisions and limitations on withdrawal.
The participant may see only:
Target Date 2055 Fund
Underneath that label may sit:
Target-date CIT → private-market CIT or feeder → conduit vehicle → private-equity partnership → portfolio company.
The industry’s public message is democratization.
Its private contracts are about control, confidentiality, fees, valuation, liquidity and avoiding look-through fiduciary status.
Before DOL offers fiduciaries a safe harbor, it should require them to obtain and analyze every governing contract below the target-date fund. If the industry says the new 401(k) contracts will be different, the answer is simple:
Show them.
Liquidity is where the deception can become a participant loss
The proposed rule identifies liquidity as one of six fiduciary factors. But liquidity cannot be reduced to a checklist entry.
As CommonSense explained in “Liquidity Is a Retirement Risk ERISA Fiduciaries Need to Start Taking Seriously”, there are two separate questions:
- Can the participant get out?
- Can the plan or target-date fund get out of its underlying investment?
A participant may trade a target-date fund every day even though its private-equity, private-credit or insurance holdings cannot be sold daily at their reported values.
Someone must provide that liquidity. During normal markets it may come from new contributions or sales of public securities. During stress, redemptions can force the liquid portion of the fund to shrink while stale private assets remain. Funds may impose gates, sell assets at discounts or shift losses toward participants who stay behind.
That creates a first-mover problem inside an investment marketed as a simple retirement default.
The central valuation question is equally simple:
If an asset cannot be sold for its reported value, why should its reported value be treated as real?
An asset does not become liquid because a CIT prints a daily unit value. Private equity does not become less volatile because its manager marks it quarterly. And a retirement fund does not become diversified merely because daily-priced public securities are combined with manager-valued private assets in one spreadsheet.
DOL should not finalize a rule built on a contaminated record
The nearly 12,000 suspect comments do not, by themselves, prove that DOL officials participated in or knew about the campaign. They do not identify the sponsor. They do not prove that every supportive comment was unauthorized.
That is why an investigation is necessary.
But DOL should not exploit uncertainty created by the missing investigation. It should not count questionable comments, leave them posted as anonymous support, summarize them as evidence of public sentiment or finalize the rule before determining who submitted them.
At minimum, DOL should:
- preserve all comments, submission metadata and internal communications;
- identify the common source or sources of the five templates;
- notify people whose identities were apparently used without authorization;
- flag disputed comments publicly rather than silently relabeling them anonymous;
- disclose the number of suspect comments and exclude them from any characterization of public support;
- refer potential violations to DOJ and the DOL Inspector General;
- release the methodology and findings of its authenticity review; and
- withdraw or suspend the proposed rule until the administrative record is trustworthy.
Bottom line
Private equity wants access to workers’ retirement savings.
Its sales pitch relies on smoothed valuations that can manufacture apparent diversification. Its contracts hide fees, conflicts, control and illiquidity beneath layers of entities. And now its political support appears to include nearly 12,000 public comments that may themselves have been manufactured.
The pattern is hard to ignore:
Smoothed numbers manufacture lower risk.
Secret contracts manufacture plausible deniability.
Fake comments manufacture public support.
DOL should not provide a safe harbor for private markets while its own public-comment process may have become a harbor for astroturfing.
Before the Department puts private equity into America’s 401(k) default funds, it must tell the public who tried to put dead people and stolen identities into the rulemaking record.
Primary sources and related CommonSense analysis
- Warren–Sanders letter to Acting Labor Secretary Keith Sonderling and EBSA Assistant Secretary Daniel Aronowitz, September 25, 2026
- Senate Banking Committee announcement
- DOL rulemaking docket EBSA-2026-0166
- GAO-19-483: Federal Rulemaking—Identity Information in the Public Comment Process
- GAO-20-383R: Selected Agencies’ Management of Public Comments
- GAO-21-103181: Public Comment Data and Their Limitations
- Private Equity’s New 401(k) Sales Pitch: Fake Diversification From Smoothed Numbers
- The Contracts Private Equity Doesn’t Want 401(k) Participants to See
- Liquidity Is a Retirement Risk ERISA Fiduciaries Need to Start Taking Seriously

