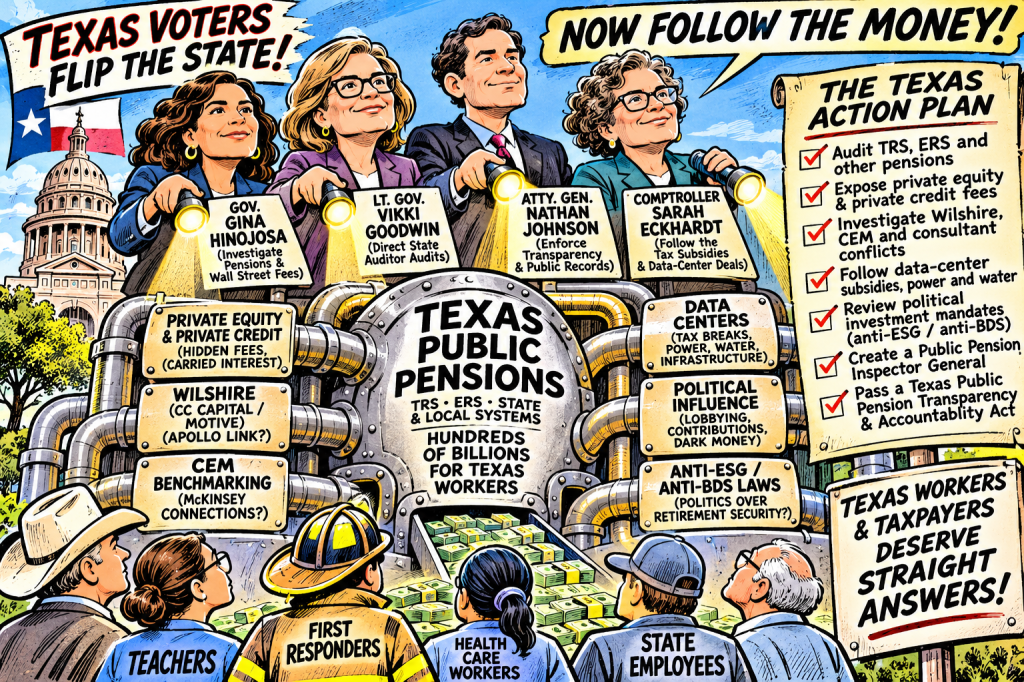
Gina Hinojosa, Vikki Goodwin, Nathan Johnson, and Sarah Eckhardt have an extraordinary opportunity to expose hidden pension fees, private-market risks, politically directed investments, and taxpayer subsidies. They should begin investigating before waiting for new legislation.
By Christopher B. Tobe, CFA, CAIA
The CommonSense 401k Project | November 4, 2026
Texas Just Had a Political Earthquake
On November 3, Texas voters delivered a historic rejection of the state’s Republican leadership.
After more than three decades of Republican governors, Democrat Gina Hinojosa defeated Greg Abbott.
Democrat Vikki Goodwin defeated Lieutenant Governor Dan Patrick.
Democrat Nathan Johnson won the attorney general’s office.
And Democrat Sarah Eckhardt defeated Don Huffines for state comptroller.
The results are historic. But the real question is what these new officials will do with the powers voters have handed them.
Texas has some of America’s largest public pension systems, an enormous private equity and private credit industry, massive data-center development, and an increasingly complicated network of public subsidies, financial managers, political organizations, and investment consultants.
These issues are interconnected.
Texas public employees and teachers contribute to pension systems investing billions of dollars through Wall Street.
Private equity managers collect fees, carried interest, and other compensation.
Data-center developers seek favorable tax treatment and public infrastructure.
Financial firms influence investment policy through lobbying, campaign contributions, trade associations, and sometimes opaque political networks.
Meanwhile, state laws can require pension trustees to make politically directed investment decisions.
The new Texas leadership has an opportunity to investigate all of it.
The good news is that much of this work can begin without passing a single new law.
1. Governor Gina Hinojosa: Open the Books
The governor should begin with a comprehensive review of Texas public pension governance.
The Teacher Retirement System of Texas (TRS) and Employees Retirement System of Texas (ERS) manage enormous retirement obligations.
Texas also has major county, municipal, and other retirement systems.
Their investment programs increasingly include private equity, private credit, real estate, infrastructure, and other investments whose true costs and risks can be difficult for beneficiaries to understand.
Hinojosa should make public pension transparency an immediate administrative priority.
She can request comprehensive information from state agencies, appoint qualified and independent officials where vacancies and statutory appointment powers permit, and propose legislation requiring greater disclosure.
But the governor cannot simply order independent pension boards to abandon investments or rewrite existing contracts.
Texas public retirement systems have statutory and constitutional governance protections.
That makes transparency, independent oversight, and carefully drafted legislation essential.
Start with the real cost of private equity
The public deserves to know more than the management fee reported in a pension system’s annual report.
Private equity managers may collect:
- Management fees.
- Carried interest.
- Transaction and monitoring fees.
- Portfolio-company payments.
- Financing and subscription-line expenses.
- Affiliate fees.
- Fees generated through continuation vehicles.
These expenses can be deducted within investment partnerships or portfolio companies rather than appearing as straightforward checks written by the pension system.
Texas should require reporting of the total economic cost borne by each pension fund, without double counting.
A public pension system should not claim to have a low-cost investment program if its reporting omits material costs embedded in private funds.
2. Lieutenant Governor Vikki Goodwin: Use the State Auditor
One of the most important election results may be Vikki Goodwin’s defeat of Dan Patrick.
Why?
Because the lieutenant governor plays an important role in overseeing the Texas State Auditor.
The State Auditor operates under the Legislative Audit Committee, jointly chaired by the lieutenant governor and the speaker of the Texas House.
Under Chapter 321 of the Texas Government Code, the State Auditor has substantial authority to examine state agencies, public expenditures, and government programs.
Goodwin should make pension investment transparency and data-center subsidies priorities for independent audit review.
The Legislative Audit Committee must follow its statutory procedures, and Goodwin cannot unilaterally direct every audit.
But she can advocate an ambitious audit agenda.
Audit the pension consultants
Texas should examine the independence of firms hired to advise pension trustees and evaluate investment performance.
The central question is simple:
Who investigates Wall Street when the investigator also has Wall Street clients or owners?
Private equity-owned consulting firms, benchmarking providers, valuation specialists, and investment-cost evaluators should disclose their beneficial ownership and material commercial relationships.
A consultant should not be treated as independent merely because its contract describes it that way.
An independent audit should determine whether consulting firms have financial relationships with the managers whose performance or expenses they evaluate.
That includes indirect ownership interests and compensation arrangements.
The investigation should also determine whether consultants recommended benchmarks that made private investments appear more successful than appropriate public-market alternatives.
3. Attorney General Nathan Johnson: Enforce the Public’s Right to Know
Texas already has a remarkably strong statement of principle in Government Code Section 552.0225.
The statute recognizes that government investments are investments made for the people and that the public is entitled to information concerning them.
It specifically identifies categories of investment information that must be disclosed.
This is a powerful starting point.
Attorney General Nathan Johnson should review how public pension systems apply these disclosure requirements.
Are pension systems providing meaningful information about private equity fees?
Are they identifying the actual investment managers and controlling entities?
Are they disclosing investment agreements and financial terms where the law requires disclosure?
Are public-records exemptions being interpreted more broadly than necessary?
The attorney general has authority to issue certain legal opinions, represent state agencies, and enforce laws within the limits of the office’s statutory jurisdiction.
The AG should use those powers to strengthen compliance with Texas public-information requirements.
However, the attorney general cannot automatically compel disclosure of every confidential partnership agreement or initiate criminal prosecutions without the jurisdiction required by law.
That is why the proposed transparency legislation matters.
It would clarify which investment economic terms must be public and establish enforceable rights for pension beneficiaries and taxpayers.
Investigate actual misconduct, not merely unpopular investments
Where evidence supports possible fraud, undisclosed conflicts, deceptive reporting, or misuse of public resources, appropriate investigative authorities should examine it.
Investment losses alone do not establish wrongdoing.
Neither does a private equity manager’s political affiliation.
The proper standard is evidence.
But confidentiality should not become an excuse for avoiding accountability.
4. Comptroller Sarah Eckhardt: Follow the Tax Subsidies
Sarah Eckhardt may have one of the most important financial accountability jobs in Texas.
The comptroller is responsible for major state tax administration, accounting, revenue estimates, and fiscal reporting.
The office also has substantial responsibilities involving state economic-development incentives.
Texas is experiencing an extraordinary expansion of data centers, AI infrastructure, electricity generation, transmission projects, and related private investment.
Companies and developers may receive state or local incentives, tax exemptions, infrastructure support, or other public benefits.
The comptroller should create a comprehensive public accounting of these arrangements.
For each material data-center project, Texans should be able to determine:
- How much private capital was invested?
- How much state and local tax revenue was forgone?
- What public infrastructure was required?
- How much electricity and water will the facility consume?
- How many permanent jobs were created?
- What is the public subsidy per permanent job?
- Who ultimately owns the project?
Existing confidentiality laws may prevent immediate release of certain taxpayer-specific information.
The comptroller should publish what current law permits and request legislation authorizing additional project-level disclosure.
The data-center question is bigger than tax breaks
Electricity demand is becoming a major economic issue.
Data centers can require substantial generation, transmission, and distribution investments.
If infrastructure costs are shifted to ordinary households and small businesses, the public may effectively subsidize private development through utility bills.
The state should independently examine these costs.
And the pension systems should disclose whether they invest in the companies financing the same projects.
Texans deserve to know whether they are subsidizing a data center as taxpayers, financing its infrastructure as ratepayers, and investing in it through their retirement savings.
Those relationships may be economically legitimate.
But they should not be invisible.
5. Railroad Commissioner Jon Rosenthal: Follow the Energy Infrastructure
Another important election result was the victory of Democrat Jon Rosenthal for the Texas Railroad Commission.
The commission regulates important parts of the state’s oil and gas industry.
Rosenthal has discussed energy costs, pollution, and data-center development.
His office can contribute to the broader investigation by examining matters within the commission’s jurisdiction, including relevant natural-gas infrastructure and pipeline issues.
However, the Railroad Commission does not generally regulate electric utility rates or approve all data-center construction.
Those responsibilities involve other authorities, including the Public Utility Commission, ERCOT, local governments, and environmental regulators.
The new administration should coordinate these agencies rather than pretend any single official controls the entire energy system.
6. Texas’s Anti-ESG and Anti-BDS Laws Need Reconsideration
Texas has adopted politically directed investment and contracting restrictions affecting financial companies and public pension systems.
Two particularly important statutes are:
Government Code Chapter 808, addressing investments in companies that boycott Israel.
Government Code Chapter 2271, imposing certain Israel-boycott-related contracting certification requirements.
Texas also has separate restrictions involving financial companies accused of boycotting energy companies.
These policies raise an important fiduciary question.
Should public pension trustees make investment decisions based on political lists established by state officials, or should they focus on investment risk, return, costs, and obligations to beneficiaries?
The new administration should review the economic consequences of these restrictions.
How much did compliance cost?
Were investment opportunities lost?
Did pension systems incur additional transaction expenses?
Were managers excluded for reasons unrelated to their expected investment performance?
The state should also examine whether these restrictions created political advantages for particular financial firms.
A consistent fiduciary standard
My position is straightforward.
Public pension assets should be managed for the benefit of participants and beneficiaries.
Trustees should be able to consider financially material environmental, social, governance, geopolitical, and human-rights risks.
But investment decisions should be supported by documented fiduciary analysis.
Neither anti-ESG politics nor an ESG label should substitute for independent investment judgment.
Texas should repeal unnecessary political investment mandates and replace them with transparent fiduciary standards.
This would require legislative action, not merely an executive order.
7. Private Equity’s Hidden Risks Deserve Their Own Investigation
Private equity and private credit create several transparency problems that are especially serious for public pension systems.
Valuations
Publicly traded stocks are generally valued using observable market prices.
Private assets often depend on models, assumptions, appraisals, and manager-controlled estimates.
This creates opportunities for delayed recognition of losses and artificially smooth reported returns.
Pension systems should disclose valuation methodologies, material overrides, appraisal delays, and differences between reported net asset values and actual secondary-market transaction prices.
Liquidity
Private investments may impose redemption restrictions, extended holding periods, and significant exit costs.
These risks become particularly important when pension systems need cash to pay retirement benefits.
Benchmarks
Private equity managers should not be permitted to justify their fees by comparing themselves with benchmarks that are easy to outperform.
Public pension systems should publish independent, low-cost, investable reference portfolios.
Conflicts
When the same financial organization advises pension trustees, manages investments, evaluates performance, and sells related products, conflicts may be difficult to identify.
The solution is full disclosure of ownership, compensation, and related-party transactions.
8. Texas Needs a Public Pension Inspector General
The existing State Auditor is an important institution.
But Texas should also consider creating an independent Office of Public Pension Inspector General.
The office should have authority to examine pension investment contracts, obtain relevant records, investigate conflicts, and report publicly.
Its leadership should be protected from arbitrary political removal.
Its budget should be sufficient to investigate complex private equity arrangements.
And it should be prohibited from hiring conflicted consultants as supposedly independent investigators.
The inspector general should coordinate with the State Auditor, attorney general, Pension Review Board, and other relevant agencies.
This would create a permanent accountability structure rather than relying on occasional political investigations.
9. I Have Prepared a Texas Legislative Model
The proposed Texas Public Pension Transparency, Accountability, and Data Center Risk Act of 2027 provides a starting point.
The discussion draft includes:
- Comprehensive private equity and private credit fee disclosure.
- Underlying investment and beneficial ownership transparency.
- Independent verification of valuations and performance benchmarks.
- Disclosure of political contributions, lobbying, and pension-related dark-money arrangements.
- Data-center electricity, water, tax subsidy, and infrastructure reporting.
- Cryptocurrency and digital-asset exposure reporting.
- Executive compensation and bonus transparency.
- Provider integrity investigations.
- Private enforcement rights for pension participants and appropriately qualified taxpayers.
- An independent pension oversight study.
- Repeal of specified anti-BDS investment and contracting restrictions.
These proposals would require review by Texas legislative counsel, particularly regarding sovereign immunity, pension trust protections, taxpayer standing, contractual rights, and constitutional limits.
But the bill provides a framework for closing disclosure gaps that existing administrative authority cannot fully address.
10. The First 100 Days: What the New Texas Leadership Should Do
The incoming officials should announce a coordinated financial transparency initiative.
Governor Hinojosa should request independent pension governance reviews, identify opportunities for appointments of qualified fiduciaries, and make transparency legislation an administration priority.
Lieutenant Governor Goodwin should seek Legislative Audit Committee approval for reviews of public pension expenses, consultant independence, and data-center subsidies.
Attorney General Johnson should review compliance with Texas investment-information disclosure requirements and examine legally supportable enforcement actions.
Comptroller Eckhardt should develop a statewide accounting of data-center tax expenditures, public subsidies, and economic-development commitments.
Railroad Commissioner Rosenthal should investigate relevant energy infrastructure and coordinate with utility and environmental regulators.
The agencies should establish clear timelines, preserve relevant records, and publish their findings.
An initial 100-day report could identify available data, major disclosure gaps, legal barriers, and recommended legislation.
Texas Has a Chance to Become the National Model
For decades, Wall Street has benefited from the complexity of public pension investing.
Private equity fees are difficult to understand.
Private credit valuations are difficult to verify.
Consultant relationships are not always transparent.
Data-center subsidies are spread across multiple government programs.
Political organizations can influence investment policy without ordinary pension beneficiaries understanding the financial consequences.
Texas has an opportunity to change that.
The November election delivered a new governor, lieutenant governor, attorney general, comptroller, and other statewide officials.
They should use the authority of their offices to begin asking questions immediately.
But they should also recognize the limits of executive power.
The strongest solution combines independent audits, lawful enforcement, public disclosure, and carefully drafted legislation.
The objective is not to replace one political investment agenda with another.
It is to restore accountability to the people whose money is being invested.
Follow the pension money.
Follow the private equity fees.
Follow the political contributions.
Follow the data-center subsidies.
Follow the electricity bills.
And when those financial trails intersect, require public officials and investment managers to explain who benefited and what it cost.
Texas voters have changed the people running the state.
Now those officials have an opportunity to change who gets to see the books.
Sources and further reading
- Texas Secretary of State — November 3, 2026 Election Results
- Texas Tribune — Democrats Seize Power in Texas
- Texas State Auditor — Authority and Responsibilities
- Texas State Auditor — Legislative Audit Committee
- Texas Comptroller — Agency Responsibilities
- Texas Pension Review Board — Statutes and Rules
- Texas Government Code §552.0225 — Public Investment Information
- Texas Government Code §552.0221 — Pension Employee and Trustee Compensation

