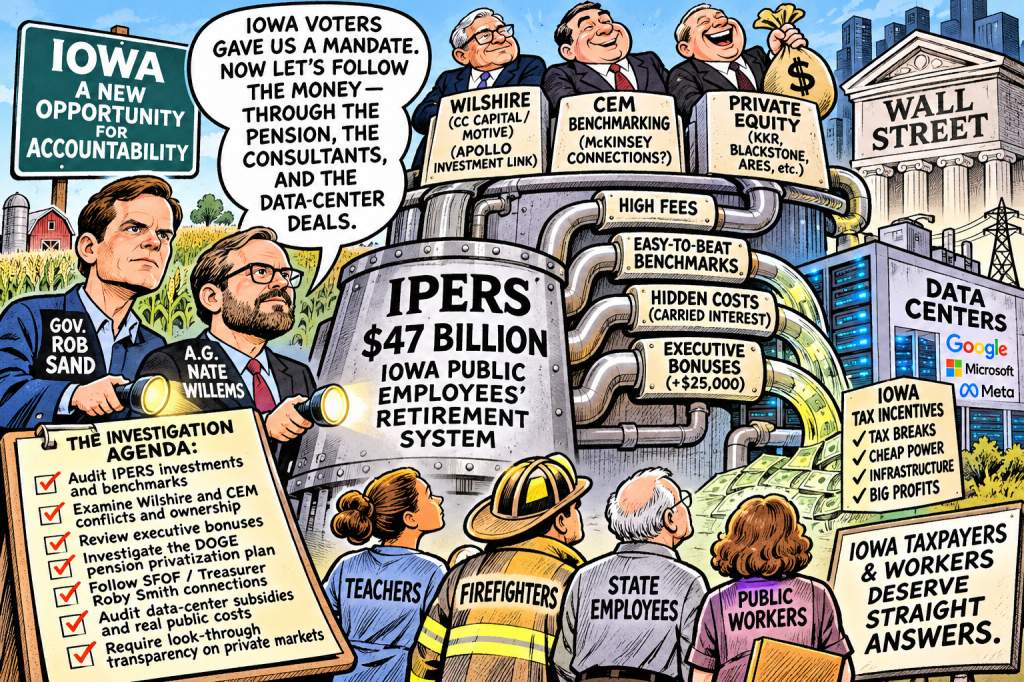
Wilshire, CEM, Apollo’s indirect connections, questionable benchmarks, hidden investment costs, and Wall Street’s influence over Iowa’s public pensions deserve a genuinely independent investigation.
By Christopher B. Tobe, CFA, CAIA
The CommonSense 401k Project | November 4, 2026
Iowa Voters Just Created an Extraordinary Opportunity
Iowa voters did something remarkable on November 3.
They elected Democrat Rob Sand as governor, defeating Republican Zach Lahn and ending Republican control of the governor’s office.
They also elected Democrat Nate Willems as attorney general, defeating Republican incumbent Brenna Bird.
Sand has spent years as Iowa’s state auditor. Willems campaigned on protecting workers, consumers, and ordinary Iowans.
Now they have an opportunity to confront one of the most important financial accountability problems in the state.
The approximately $47 billion Iowa Public Employees’ Retirement System (IPERS) has been engulfed in questions about investment performance, hidden private equity fees, misleading benchmarks, executive compensation, and the independence of Wall Street consultants.
Meanwhile, Iowa is handing out substantial tax incentives to data centers operated by Google, Microsoft, Meta, and others.
These may appear to be separate stories.
They aren’t necessarily.
Public pension money flows into private equity, private credit, real estate, and infrastructure. Those same financial markets increasingly finance data centers, electricity generation, transmission, and artificial intelligence infrastructure.
Iowa taxpayers help subsidize the facilities.
Iowa ratepayers help support the electrical infrastructure.
Iowa public employees supply billions of dollars to Wall Street investment managers.
And the investment managers collect fees.
The new governor and attorney general should investigate both sides of this transaction.
The important question is not whether every investment or tax incentive is improper.
It is why the public cannot easily determine where all the money goes.
Timothy Tucker Has Already Done Much of the Investigative Groundwork
One of Iowa’s most important independent investigative journalists is Timothy C. Tucker, founder of Restoring Democracy’s Promise.
Tucker has produced a remarkable series of investigations into IPERS, using court documents, payroll records, public-records requests, and government filings.
His reporting deserves the attention of the incoming Sand administration.
A former IPERS investment risk and operations officer, Rich Wiggins, filed litigation alleging serious problems involving the pension fund’s investment risk reporting, performance benchmarks, management fees, and executive compensation.
Wiggins alleged that substantial portions of the portfolio were benchmarked in ways that made underperformance difficult or impossible to identify.
He also alleged that the fund understated the true costs of private-market investments.
These are allegations in pending litigation, not established findings of wrongdoing.
But the lawsuit survived an important motion to dismiss in April 2026.
The issues warrant an independent examination.
Tucker’s April investigation, Newly Obtained Amended IPERS Lawsuit Expands Allegations on Risk, Fees, and Benchmarking, describes the allegations in detail.
His May follow-up, A Resignation Is Not an Audit, makes another important point.
Changing pension executives does not establish whether the underlying investment practices were appropriate.
Former IPERS CEO Greg Samorajski resigned in 2026, and other senior personnel changes followed.
But personnel changes are not a substitute for forensic accounting.
The public deserves an investigation of the money, not merely an explanation of the personnel changes.
Tim McGlinn Exposes the Benchmarking Problem
Investment professional Tim McGlinn, CFA, writing at The AltView, has produced some of the most important independent analysis of IPERS investment performance.
His April 24 article, Motion Denied! IPERS Update, Featuring Wilshire and CEM Benchmarking, identifies several troubling practices.
Among them:
- Private-market investments reportedly benchmarked against their own returns, potentially eliminating meaningful tracking error.
- Passive international equity investments appearing to generate persistent benchmark outperformance.
- Hedge-fund exposures compared against Treasury bills despite substantially different risks.
- Investment overlays that complicate the interpretation of asset-class returns.
- Cost comparisons that exclude significant categories of private-market expenses.
The self-benchmarking problem is especially serious.
Imagine a private equity portfolio loses 20%.
If the benchmark is effectively the portfolio’s own return, the investment can lose money while reporting little or no underperformance against that benchmark.
The pension system can appear to have met its performance standard even when its members have suffered significant investment losses.
This is not a meaningful test of whether private equity justified its costs and risks.
McGlinn also argues that a conventional stock-and-bond reference portfolio provides a much less flattering comparison with IPERS’s reported results.
Such comparisons require careful matching of risk, asset allocation, and time periods. But that is precisely why the pension system should publish independent, investable reference benchmarks alongside its internally constructed policy benchmarks.
A benchmark should measure performance. It should not manufacture success.
Wilshire: Who Is Really Advising Iowa’s Pension Fund?
IPERS identifies Wilshire as its investment management consultant.
Wilshire has worked with IPERS for decades.
In 2021, Wilshire announced an expanded six-year contract covering private markets advisory services and risk analytics.
That creates an obvious question.
If IPERS’s investment benchmarks and risk reporting have serious weaknesses, what did its consultant know, recommend, review, or approve?
Wilshire is also no longer simply an independent consulting firm owned by its employees. It is tied to Apollo Global Management in its structure a manager for IPERS and the owner of a leading insurer in the state Athene.
When a private-equity-owned consultant evaluates private equity investments, what conflicts exist between its owners’ commercial interests and its responsibility to pension beneficiaries?
Wilshire’s ownership and potential conflicts should be fully disclosed.
The review should identify:
- Current beneficial owners and ownership percentages.
- Any Apollo-related indirect economic interests.
- Material relationships between Wilshire, its owners, and IPERS investment managers.
- Compensation from private equity firms and other institutional clients.
- The role Wilshire played in constructing, reviewing, or approving IPERS benchmarks.
CEM Benchmarking: How Can Iowa Be So Cheap When Its Fees Are So High?
The second consulting relationship deserving scrutiny is CEM Benchmarking.
IPERS has used CEM to compare its investment expenses with those of other public pension systems.
McGlinn reports that CEM repeatedly characterized IPERS as exceptionally low-cost.
But the problem is what gets counted.
According to reporting on IPERS’s December 2025 investment board meeting, the system’s reported investment costs of approximately 13.7 basis points could increase to roughly 70 basis points when estimated private equity and private credit incentive fees and carried interest were included.
That is an extraordinary difference.
On a $47 billion portfolio, those two expense rates imply:
| Expense measure | Annualized cost |
| 13.7 basis points | $64.4 million |
| 70 basis points | $329.0 million |
| Difference | $264.6 million |
These are illustrative calculations using a common $47 billion asset base, not independently audited IPERS expense totals. The 70-basis-point figure includes estimated costs and may not be directly comparable with the narrower reported measure.
Nevertheless, the difference is enormous.
A cost comparison that excludes carried interest, incentive fees, and underlying private equity expenses can make an expensive investment program look inexpensive.
CEM’s methodology may have been applied consistently within its peer group. But that does not answer whether the comparison captures the full economic cost borne by Iowa pension beneficiaries.
There is also an ownership issue.
CEM has been linked to McKinsey, one of the world’s most influential consulting firms, which maintains substantial relationships throughout the private equity industry.
Iowa should establish CEM’s current ownership, relevant commercial relationships, and the independence of its methodology.
Who evaluates the evaluators?
That question should be central to the new administration’s pension investigation.
The Bonus Problem: Two Basis Points of Outperformance
Timothy Tucker uncovered another extraordinary issue.
IPERS Chief Investment Officer Sriram Lakshminarayanan received three consecutive annual payments of $25,000 categorized as exceptional job performance pay, according to Tucker’s examination of payroll records.
For fiscal 2025, IPERS reported an investment return of 9.87%.
Its policy benchmark returned 9.85%.
That is an excess return of just two basis points.
On $47 billion, two basis points represents approximately $9.4 million, although that arithmetic does not establish that the excess return caused any particular bonus.
The larger issue is the compensation formula.
If investment managers can influence the benchmarks used to evaluate their performance, and those benchmarks influence their compensation, an obvious conflict arises.
Tucker’s August investigation, The Formula Behind the $25,000: What Iowa’s Next Governor Inherits, examines the compensation documents.
McGlinn subsequently connected the incentive structure to the broader benchmark debate in IPERS: From Fake Outperformance to Real Cash Bonuses.
An independent investigation should determine whether the compensation system rewarded genuine investment skill or results measured against insufficiently demanding benchmarks.
This does not require assuming that any executive violated the law.
It requires independently examining the benchmarks, performance calculations, and compensation approvals.
Iowa DOGE: Was Pension Privatization Becoming a Business Opportunity?
The pension controversy extends beyond investment management.
Former Governor Kim Reynolds established an Iowa DOGE task force to recommend government efficiency measures.
One participant was Kathy Kay, an executive vice president at Principal Financial Group.
The task force recommended replacing traditional IPERS participation for new employees with a defined-contribution-style retirement arrangement.
Principal is a major provider of 401(k) and other retirement products.
That combination deserves scrutiny.
Tucker’s August 2025 investigation, Hidden Conflict Could Hand $42.9 Million to Iowa Task Force Member’s Firm, modeled the potential financial consequences.
His analysis estimated that the proposed arrangement could generate approximately $143 million in investment-management fees over ten years.
Under an illustrative scenario in which Principal obtained 30% of the business, approximately $42.9 million could flow to Principal.
Those figures are modeled possibilities, not established revenues or evidence that Principal would win the business.
But the conflict question remains.
Why was an executive of a retirement-services company participating in a government process that could create new business opportunities for companies in that industry?
Were the relationships disclosed?
Were conflicts evaluated?
Was an independent economic analysis performed?
The new governor should preserve traditional pension benefits while independently evaluating any proposal that shifts investment and longevity risks from the pension system onto individual public employees.
Iowa’s Anti-ESG Network Reaches Directly Into IPERS
Another connection deserves attention.
Iowa Treasurer Roby Smith is affiliated with the State Financial Officers Foundation, or SFOF.
SFOF has been an important organization in the national campaign against ESG investing.
But Smith is not simply a politician expressing views about investment policy.
He also serves as an ex officio voting member of the IPERS Investment Board.
That board exercises meaningful authority over pension investment policy and investment service providers.
This creates a direct institutional connection:
SFOF → Iowa Treasurer Roby Smith → IPERS Investment Board → public pension investment oversight.
Smith was reelected in November 2026, meaning the incoming Sand administration will inherit this relationship.
I have previously examined similar connections involving Ohio and Kentucky.
In my article, Allison Ball’s ESG Shell Game: Follow the Money From Kentucky to KKR to SFOF, I argued that anti-ESG politics should not become a distraction from more fundamental investment conflicts.
The same principle applies in Iowa.
If SFOF-affiliated officials believe pension funds should not use retirement money for political objectives, they should apply that standard consistently.
That means examining private equity managers, private credit firms, infrastructure investors, and investment consultants—not merely public-market managers criticized for ESG policies.
The next investigation should compare SFOF’s corporate sponsors with IPERS investment managers and consultants.
It should examine relevant political contributions, meetings, contracting decisions, and recusals.
Membership in SFOF is not evidence of improper conduct.
But public pension governance should be transparent enough to establish whether political relationships affected financial decisions.
Apollo, Athene, and Iowa’s Insurance Industry
Iowa is also an important insurance state.
Athene, the retirement-services and annuity company associated with Apollo Global Management, has substantial Iowa operations.
Apollo’s ownership of Athene places the company within the broader private equity and insurance ecosystem that has attracted increasing scrutiny over private credit, affiliated investments, and opaque valuations.
Athene’s Iowa employment footprint makes it an important economic stakeholder.
Iowa’s new administration should examine how the state’s insurance industry, private credit investments, and public pension assets interact.
The Wilshire-Motive-Apollo relationship adds another reason to require complete ownership disclosures.
The inquiry should also identify any material political contributions or lobbying by relevant firms and their executives, distinguishing individual contributions from corporate spending and verified relationships from speculation.
Iowa should not wait for another financial crisis before requiring meaningful transparency from institutions managing long-term retirement promises.
Iowa’s Data-Center Gold Rush: Follow the Taxpayer Money
The second major investigation should focus on Iowa’s data centers.
Google, Microsoft, Meta, and other companies have invested billions of dollars in Iowa facilities.
These investments provide economic benefits, including construction activity, permanent employment, and tax revenues.
But Iowa also offers significant tax exemptions and other incentives.
Qualifying data centers can receive exemptions involving equipment, cooling infrastructure, electricity, and other eligible purchases, subject to statutory conditions and limitations.
The state should publish the value of these incentives by project.
How much tax revenue is Iowa giving up?
How many permanent jobs are created?
How much electricity and water do these facilities require?
Who pays for the transmission lines and power generation necessary to support them?
And are ordinary households and small businesses subsidizing infrastructure built primarily for large technology companies?
These questions become particularly important as artificial intelligence accelerates electricity demand.
The Sand administration should commission an independent statewide data-center cost-benefit audit.
It should calculate the total public subsidy per permanent job and identify which infrastructure costs are paid by developers, utilities, taxpayers, and ratepayers.
The point is not to declare every data center a bad investment.
It is to determine whether the public is receiving a fair return.
Now Follow the Pension Money Into the Same Industry
As of March 2025, IPERS held approximately $44.7 billion in assets, with roughly 31% invested in private markets.
That included approximately:
- $7.9 billion in private equity.
- $3.1 billion in private real assets.
- $2.8 billion in private credit.
IPERS investment records identify relationships with major alternative-investment managers, including Blackstone, Brookfield, Ares, KKR, and others.
These firms participate in financial markets that increasingly fund digital infrastructure, electricity generation, transmission, and data centers.
This does not establish that a particular IPERS fund financed a particular Iowa data center.
That is precisely the disclosure problem.
A pension report identifying an investment as private equity or infrastructure tells beneficiaries little about the underlying businesses and projects.
IPERS should publish a look-through report identifying its direct and indirect exposures to data centers, AI infrastructure, power generation, utilities, digital infrastructure, and related private credit.
For each material exposure, the public should be able to identify the manager, underlying assets, investment value, leverage, valuation method, fees, carried interest, and relevant conflicts.
Iowa taxpayers deserve to know where their tax incentives go.
Iowa public employees deserve to know where their pension contributions go.
Sometimes those financial trails may intersect.
That is why the investigations should be conducted together.
What Governor Sand and Attorney General Willems Should Do
The election creates an opportunity, but the governor and attorney general do not possess unlimited authority over IPERS, private contracts, or local economic-development arrangements.
The Republican-controlled Legislature will remain an important obstacle to statutory reform.
The new administration should therefore begin with powers already available under Iowa law, pursue voluntary disclosure, and seek legislation where necessary.
I would recommend seven immediate priorities.
1. Commission an independent IPERS forensic review.
Examine investment performance, benchmarks, risk reporting, total economic costs, consultant conflicts, and executive compensation. Use investigators with no material financial relationship to the managers being evaluated.
2. Review Wilshire and CEM Benchmarking.
Require complete ownership and conflict disclosures. Independently evaluate the methodologies used to measure private-market performance and costs.
3. Investigate the Wiggins allegations.
Preserve relevant records and review the issues raised in the pending litigation, while respecting the judicial process and the rights of all parties.
4. Audit Iowa’s data-center subsidies.
Publish project-level public costs, permanent jobs, electricity and water requirements, infrastructure obligations, and subsidy effectiveness, subject to lawful confidentiality protections.
5. Require private-market look-through transparency.
Identify underlying investments, fees, carried interest, leverage, valuation assumptions, and material data-center and energy exposures.
6. Review political and commercial conflicts.
Examine the Iowa DOGE pension proposal, Principal-related conflict questions, SFOF relationships, political spending, and investment-provider contracting.
7. Pursue an Iowa Public Pension Transparency and Accountability Act.
The legislation should establish enforceable disclosure requirements, independent valuation and benchmarking, whistleblower protections, meaningful conflict rules, and appropriate judicial remedies.
An independent public pension inspector general would be a particularly important structural reform.
The Election Was Only the Beginning
Rob Sand has spent years presenting himself as an independent-minded auditor willing to challenge government waste and misconduct.
Nate Willems has promised greater attention to workers and consumers.
Now they have an opportunity to apply those principles to one of Iowa’s largest financial institutions.
They need to look closer at IPERS executives, Wilshire, CEM, Principal, Apollo, demand records, examine conflicts, independently verify performance and expenses, and publish the findings.
The public pension system belongs to Iowa’s public employees and retirees.
The tax revenue belongs to Iowa’s taxpayers.
The electrical infrastructure serves Iowa’s communities.
And the government officials overseeing these resources owe the public accountability.
Timothy Tucker and Tim McGlinn have already identified important questions.
The new administration has an opportunity to turn those questions into a comprehensive, independent examination.
The CommonSense lesson from Ohio, Kentucky, and now Iowa is simple:
Follow the pension money.
Follow the private equity fees.
Follow the consultants.
Follow the political relationships.
Follow the data-center subsidies.
And follow the electricity bills.
In Iowa, follow the money twice—once from taxpayers into the data centers, and again from public employees through Wall Street.
If those trails intersect, the public deserves to know who benefited, what risks were taken, and how much was paid along the way.
Selected sources and further reading
- Timothy C. Tucker, Newly Obtained Amended IPERS Lawsuit Expands Allegations on Risk, Fees, and Benchmarking, April 2026.
- Timothy C. Tucker, A Resignation Is Not an Audit, May 2026.
- Timothy C. Tucker, The Formula Behind the $25,000, August 2026.
- Timothy C. Tucker, Hidden Conflict Could Hand $42.9 Million to Iowa Task Force Member’s Firm, August 2025.
- Tim McGlinn, Motion Denied! IPERS Update, Featuring Wilshire and CEM Benchmarking, April 2026.
- Tim McGlinn, IPERS: From Fake Outperformance to Real Cash Bonuses, September 2026.
- Tim McGlinn, Two-ish Percent Is the New 4–6%: Private Equity’s New World, Featuring Wilshire, October 2026.
- IPERS FY2025 Annual Comprehensive Financial Report.
- Iowa Public Radio — 2026 election coverage.
- The CommonSense 401k Project, Kentucky’s Pension Fee Bounty: Who Investigates Apollo When Apollo Is Connected to the Investigator?.

