By Christopher B Tobe CFA CAIA
The CommonSense 401k Project | November 18, 2026
Wall Street’s latest target-date announcement strengthens the case for federal 401(k) transparency legislation. Retirement savers need enforceable rights to examine the assets, fees, valuations, conflicts, and withdrawal restrictions beneath a familiar retirement-fund label. Target date fund hold over 50% of 401(k) assets and are the fastest growing and usually the default option.
On November 9, Manulife John Hancock announced Lifetime Blend+, a proposed target-date collective investment trust series with Great Gray as expected trustee. Still in development and subject to approval, the strategy anticipates up to 20% in private markets, alongside affiliated CITs and stable-value products. The planned mix includes private equity, private credit, infrastructure, and real estate. [1]
Those features make this an immediate test of the protections in my proposed 401(k) Private Equity Transparency Act. Congress should establish the disclosure rules before these structures become routine destinations for workers’ default retirement contributions.
The Nevada connection deserves scrutiny
Great Gray is a Nevada-chartered trust company, as its published trust declaration identifies and Nevada’s financial regulator’s licensee list confirms. That establishes the proposed trustee’s charter; final Lifetime Blend+ trust and participation documents should establish the new product’s precise governing law and terms. [2, 3]
The announcement says the proposed funds and their units will be exempt from registration under the Investment Company Act of 1940 and Securities Act of 1933, respectively. Great Gray is expected to retain ultimate fiduciary authority. [1]
State trust supervision and ERISA duties matter. But workers deserve public, standardized investment disclosures regardless of the charter chosen by a financial institution. My proposed legislation would require identification of the actual regulator, jurisdiction, ownership chain, and underlying vehicles, together with enforceable access to the financial information.
A nationally distributed retirement product should face a national transparency floor. A Nevada charter should never become a substitute for explaining what workers own.
The Principal layer cake is becoming an industry model
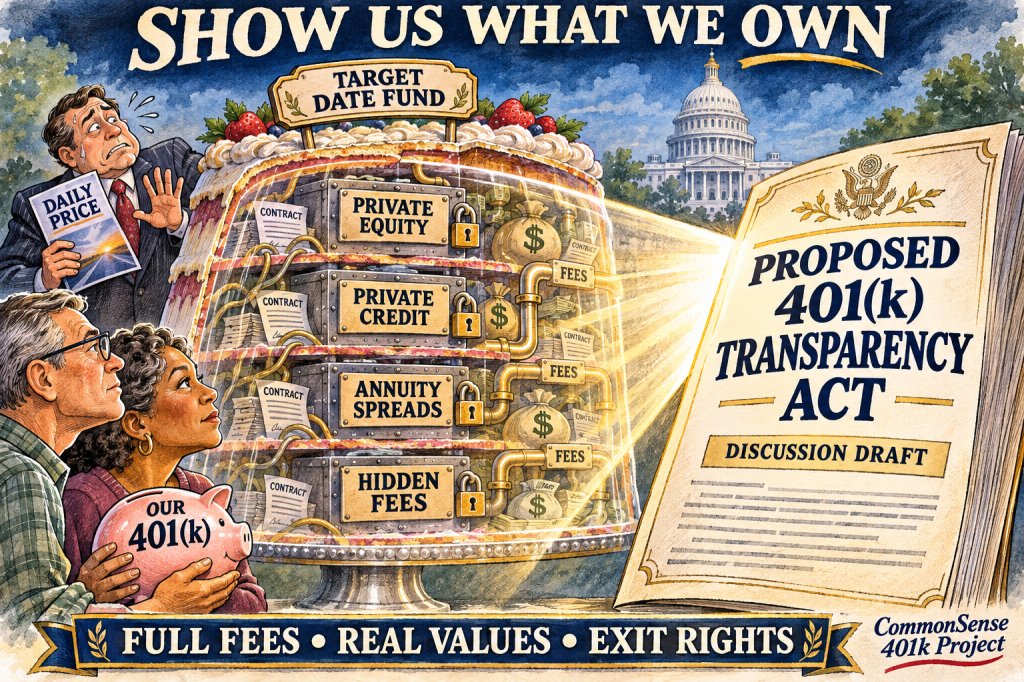
In September, I described Principal’s private-market expansion as an “illiquidity layer cake.” The concern was the accumulation of investment vehicles, contracts, fees, and exit restrictions underneath one participant-facing label. [4]
Principal’s August announcement proposed CIT structures combining public and private strategies. Its disclosure acknowledges that routine participant transactions may be supported by other investments, while liquidity or valuation conditions can sometimes delay, limit, or interrupt processing. That warning concerns Principal’s arrangements; it does not establish Lifetime Blend+’s final terms. [5]
The comparison is structural. Adding liquid securities around private assets can help manage routine withdrawals. It cannot guarantee that the underlying private investments can be sold promptly at reported values during stress.
Plan fiduciaries should demand the complete contractual answer before selecting such a fund, especially as a default investment.
A daily price must be supported by current valuations
The proposed Lifetime Blend+ structure is intended to provide daily valuation and participant-directed operations. [1] That raises a question every retirement committee should ask: how will the daily transaction price reflect private assets whose values depend on estimates?
The existence of a price on a screen does not establish that each underlying investment can be sold at that price. Nor does it establish that the price fairly allocates value among participants entering, withdrawing, and remaining in the fund.
My draft would require a common fair-value measurement framework inside target-date funds, supported by current assessments of material events. It would also require separate disclosure of manager-reported values, contractual book balances, estimated exit proceeds, and the differences among them.
Different assets can require different valuation techniques within a consistent accounting framework. The problem is presenting incompatible or unreconciled measures as though every reported dollar means the same thing.
The private equity sensitivities in my proposal illustrate why this matters. Suppose a hypothetical $100 million fund has $20 million of private equity at manager-reported value. Valuing that sleeve at 90, 80, or 70 cents per reported dollar reduces the total by $2 million, $4 million, or $6 million, holding everything else constant. Those are illustrative calculations, not estimates of this proposed product’s value or claims about current market discounts.
Participants should be able to see that sensitivity before a market shock exposes it.
Who bears the cost when liquid assets leave first
Consider another hypothetical $100 million portfolio, with $20 million in illiquid investments. If $25 million of withdrawals is funded entirely from liquid assets, the remaining $75 million contains the same $20 million illiquid sleeve. Its weight rises from 20% to approximately 26.7%, before market changes, costs, or rebalancing.
That is the arithmetic of concentration. It is not a forecast for Lifetime Blend+.
My proposal would require withdrawal stress tests of 10%, 25%, and 40% over 30 and 90 days, incorporating contractual restrictions and examining the consequences for remaining participants. Fiduciaries need to know who bears sale discounts, borrowing costs, or deviations from the intended glide path.
Stable value/Fixed Annuities require their own investigation
The announcement includes stable value, but it does not establish the final contract structure. Fiduciaries must obtain that information rather than assume that all stable-value arrangements are equivalent.
Where insurance contracts support an investment, the required inquiry should identify the issuer, assets legally owned by the plan or trust, contractual guarantees, retained spreads, credit exposure, and separate participant and plan-level withdrawal rights.
My draft would require insurers to reconcile supporting-asset earnings, participant credits, expenses, and retained product earnings. It would distinguish gross spread from profit after expenses. It would also disclose estimated plan-exit proceeds, surrender charges, market-value adjustments, and enforceable payment dates.
A participant’s ordinary withdrawal at book value and a plan’s ability to replace a provider are different rights. Both belong in the analysis.
Follow the compensation through every layer
The announced investment lineup includes Apollo, J.P. Morgan, StepStone, and Townsend, together with Manulife investment capabilities. [1] Naming respected managers does not answer what the complete structure will cost or how each provider is paid.
The question is the total economic burden: top-level expenses, underlying management fees, performance compensation, financing costs, affiliate payments, trustee charges, platform economics, and any offsets or revenue sharing. Disclosure must prevent double counting while identifying costs that never appear as a separate participant invoice.
My bill would trace those amounts through the investment chain and require consultants to disclose ownership, compensation, referral arrangements, and relationships with recommended providers. It would also require a written Investment Policy Statement, public filing, and documented explanations of material departures.
These requirements do not establish that the new product has undisclosed improper payments. They establish the evidence every provider should supply before fiduciaries commit workers’ money.
Congress should act before the defaults change
My November 3 legislative discussion draft remains a proposal for congressional consideration. As described in my November 7 announcement, it would combine public Form 5500 reporting, independent examination, provider obligations, participant disclosure rights, and enforcement. [6]
The product’s own risk disclosure acknowledges potential private-market disadvantages involving liquidity, valuation, fees, and information. [1] Those risks deserve measurable evidence and enforceable contractual answers.
If providers can demonstrate better retirement outcomes after all costs and risks, they should disclose the data needed to test that claim. Workers should be able to compare the result with simpler, transparent alternatives.
New target-date products make the legislative need concrete. Before retirement savings move into increasingly complicated structures, Congress should require Wall Street to show the underlying investments, explain the prices, disclose the complete compensation, and demonstrate how participants can get their money out.
Sources and related reading
[1] Manulife John Hancock Retirement, Lifetime Blend+ announcement, November 9, 2026. Read source
[2] Great Gray Trust Collective Investment Trust for Stable Value Funds, 2023 amended declaration, opening paragraph identifying the Nevada-chartered trustee. This is evidence of the trustee’s charter, not the final Lifetime Blend+ contract. Read source
[3] Nevada Financial Institutions Division, Retail Trust Companies list. Read source
[4] Principal Is Building an Illiquidity Layer Cake for Your 401(k), September 7, 2026. Read source
[5] Principal Expands Featured Partner Program to Support Private Market Access in Retirement Plans, August 26, 2026. Read source
[6] New Federal 401(k) Transparency Legislation Proposed, November 7, 2026; and the November 3, 2026 expanded legislative discussion draft. Read source
Related reporting: 401(k) Specialist, Manulife John Hancock and Great Gray plan target-date CITs with private markets exposure. Read source

