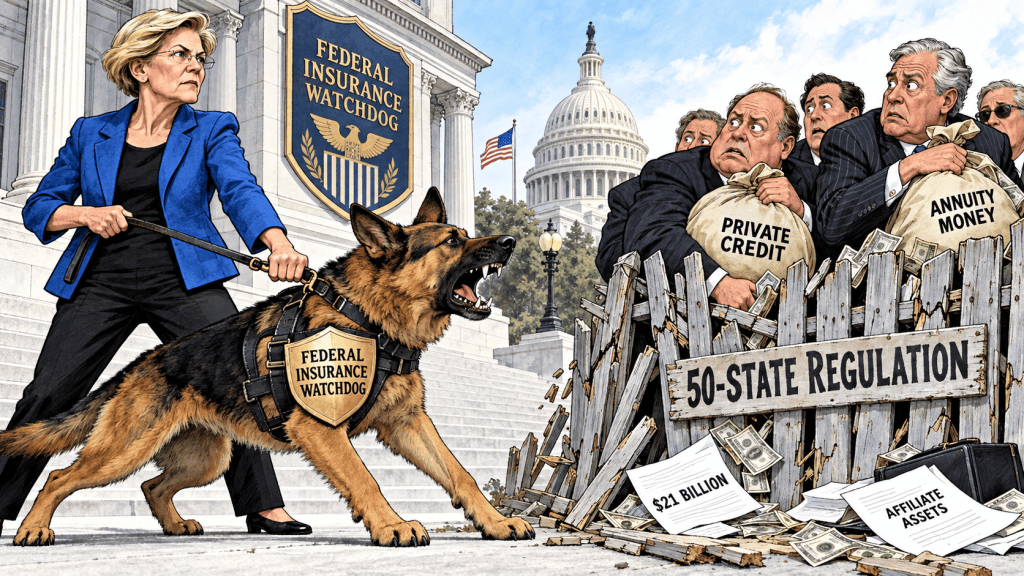
Senator Elizabeth Warren may be the only major figure in Washington asking the insurance industry the questions its state regulators have spent years avoiding.
Her September 10 letter to the National Association of Insurance Commissioners is ostensibly about billionaire Mark Walter, Delaware Life, Clear Spring Life and the growing entanglement between private-equity firms, private-credit managers and life insurers.
But Warren’s questions go far beyond Walter.
She is really asking whether America’s fragmented, industry-dominated state insurance regulatory system is capable of regulating modern life insurers at all.
The answer increasingly appears to be no.
Private-equity firms have discovered that insurance companies provide enormous pools of permanent capital. Annuity buyers and pension retirees supply the money. The insurer invests that money in private credit, affiliated assets, structured products, commercial real estate loans and offshore reinsurance arrangements. The asset manager collects fees and spreads. When something goes wrong, policyholders, other insurers and ultimately taxpayers are expected to absorb the damage.
Warren is one of the few people in Washington willing to challenge that machine.
The Mark Walter Scandal Is a Regulatory Autopsy
Warren’s letter focuses on reports that two insurers owned by Walter’s TWG Global—Delaware Life and Clear Spring Life and Annuity—may have misclassified approximately $21 billion of investments as independent even though the money allegedly flowed through intermediaries to businesses connected with Walter.
After the reporting was corrected, Delaware Life’s disclosed affiliated investments reportedly jumped from approximately 3 percent to 42 percent.
That is not a minor accounting disagreement.
Affiliate classifications go to the heart of whether regulators, policyholders and rating agencies can see an insurer’s concentration, conflicts of interest and liquidity risk. If an insurer can route money through an intermediary and make an affiliated exposure appear independent, statutory filings may provide only an illusion of transparency.
Warren therefore asks the NAIC exactly the questions that should have been asked before journalists and a whistleblower reportedly brought the situation to light:
- What did regulators do after learning about the apparent misclassifications?
- Are other insurers using similar structures?
- Can insurers use the “filing-exempt” process to bypass meaningful NAIC review?
- Has the NAIC identified other private firms making risky investments with policyholder premiums?
- Does the NAIC believe insurer investment disclosures are adequate?
- Are insurers owned by private-investment firms less transparent?
- Can state guaranty funds withstand losses resulting from private-credit exposure?
- Are federal guardrails now necessary?
These are devastating questions because the insurance industry cannot answer them honestly without exposing the weakness of the existing system.
Read Warren’s September 10 letter to the NAIC.
Private Credit Has Outgrown State Regulation
Warren notes that life-insurer private-credit investments more than doubled—from approximately $386 billion in 2014 to $849 billion in 2024.
The state regulatory system did not double its sophistication, staffing, transparency or enforcement capability during that period.
Instead, insurers and asset managers created increasingly complicated networks of affiliated lenders, private funds, special-purpose vehicles, offshore reinsurers and privately rated securities. Assets that do not trade in public markets can be valued through models, manager estimates or ratings purchased from firms selected by the issuer.
That permits risk to remain hidden until somebody needs to sell the asset.
Insurance liabilities may be long-term, but they are not infinitely patient. Policyholders surrender contracts. Pension annuitants need monthly checks. Collateral calls arise. Federal Home Loan Bank advances can disappear. Reinsurance recoverables can become disputed. Ratings downgrades can force additional capital requirements precisely when capital and liquidity are hardest to obtain.
Private credit’s defenders repeatedly say that illiquidity does not matter because life insurers hold assets to maturity.
That is the same comforting argument Wall Street always makes before a liquidity crisis.
The NAIC Is Not a Regulator
The name “National Association of Insurance Commissioners” creates the impression of a national regulatory agency.
It is not.
The NAIC is a private standards-setting and coordinating organization. It develops models and facilitates cooperation, but it does not function like the SEC, FDIC, Federal Reserve or Consumer Financial Protection Bureau. It cannot provide uniform federal supervision of nationwide insurance complexes.
Actual authority remains scattered among state insurance departments with different laws, budgets, expertise and political cultures.
That fragmentation is extremely valuable to the insurance industry. A multibillion-dollar insurer can select a favorable domicile while selling products throughout the country. No single state regulator has the same incentive, resources or national responsibility that a genuine federal regulator would have.
Iowa, for example, has acquired an enormous national responsibility because so many annuity and private-equity-related insurance structures are domiciled there. Yet retirees and policyholders in every other state must depend on Iowa regulators to understand and police risks that could eventually reach them.
This is regulation by regulatory arbitrage.
State Guaranty Associations Are Not the FDIC or PBGC
The industry’s final defense is always the state guaranty-association system.
That defense is dangerously misleading.
State guaranty associations are not meaningfully prefunded national insurance. They generally operate by assessing surviving insurers after another insurer has failed. Assessment capacity is limited, coverage differs among states, and benefits are subject to statutory caps and exclusions.
Even worse, as Warren’s letter emphasizes, insurers may receive state premium-tax credits for the assessments they pay. That means the cost of an insurer failure can eventually be shifted to state taxpayers.
Private equity keeps the fees during the good years.
Policyholders, competing insurers and taxpayers inherit the losses during the bad years.
The system might be able to manage the isolated failure of a traditional insurer. It has never been tested against the failure of a giant, interconnected insurance complex loaded with private credit, affiliated assets, structured products and offshore reinsurance.
Nor has it been tested against multiple insurers suffering losses from the same private-credit downturn.
In that situation, the supposedly healthy insurers being assessed to finance the rescue may own similar assets and face the same liquidity pressure. The guaranty mechanism could become procyclical—demanding cash from the industry at the moment cash is most scarce.
As I have previously written, calling this system insurance is generous. It is principally a post-failure assessment mechanism dressed up to reassure annuity buyers.
State Guaranty Associations Behind Annuities Are Still a Joke.
Retirees Are Being Forced to Accept Risks They Cannot Escape
The regulatory failure becomes even more serious when an employer transfers pension obligations to an insurer.
In a pension-risk-transfer transaction, retirees can lose:
- The plan sponsor’s continuing contribution obligation;
- ERISA’s fiduciary and funding protections;
- PBGC protection;
- Diversification across pension-plan assets; and
- The ability to hold fiduciaries accountable before an insurer actually defaults.
They are left with the promise of a single insurer.
They ordinarily cannot sell that promise, diversify it, return to the pension plan or demand a safer insurer when credit quality deteriorates. Most contracts appear to lack a meaningful downgrade provision that would require collateral, additional protection or transfer to a stronger company before insolvency.
Yet courts have ruled that retirees suffer no cognizable injury while the insurer continues mailing checks.
That is financially illiterate.
Risk has value. Diversification has value. Federal protection has value. A downgrade escape provision has value. Taking those protections away causes an injury when the transfer occurs—not merely years later when the insurer finally misses a payment.
Judge Says Lumen Retirees Have No Injury—Because the Athene Time Bomb Hasn’t Exploded Yet.
Security Benefit Shows Why Walter Is Not an Isolated Case
Mark Walter is not the entire problem.
Security Benefit may present an even more important warning because its annuities are embedded throughout the retirement system, particularly in teacher 403(b) plans.
Its history involves private-equity ownership, complex affiliate relationships, reinsurance transactions, private assets and a state guaranty system that was never designed to manage the failure of a major insurer operating within a broader private-capital empire.
Principal is simultaneously constructing target-date and retirement products that can layer private equity, private debt, illiquid real estate and annuity guarantees inside state-regulated collective investment trusts.
Participants may think they own a diversified retirement fund. Economically, they may be accepting several layers of illiquidity, valuation discretion, insurer credit exposure and conflicts of interest.
That is why the Walter investigation cannot end with Delaware Life and Clear Spring. Regulators must examine the entire private-equity-insurance model.
Security Benefit May Be the Biggest Annuity Risk Since AIG.
Principal Is Building an Illiquidity Layer Cake for Your 401(k).
The CFPB Model Is the Insurance Industry’s Worst Nightmare
CFPB—the Consumer Financial Protection Bureau.
Current federal law generally excludes the “business of insurance” from the CFPB’s jurisdiction. Warren’s letter does not expressly propose turning the CFPB into the national insurance regulator.
But it points directly toward the need for a CFPB-style federal insurance watchdog with the authority to:
- Examine nationwide insurance groups and their affiliates;
- Obtain transaction-level information about private assets;
- Review affiliated investments and reinsurance arrangements;
- Establish uniform disclosure requirements;
- Receive and analyze policyholder complaints;
- Require disclosure of annuity spreads, compensation and surrender restrictions;
- Examine the financial capacity of state guaranty associations;
- Require credible insurer resolution plans;
- Impose meaningful penalties; and
- Act before policyholders suffer an irreversible loss.
That is the insurance industry’s worst nightmare.
A real federal regulator would eliminate the ability to shop for the friendliest state domicile. It could compare the same practices across companies and states. It could follow assets through affiliated funds, intermediaries and offshore reinsurers. It could publish national data instead of forcing consumers to decipher fifty different regulatory systems.
Most importantly, it could treat annuity owners as financial consumers entitled to understandable disclosures and enforceable protections.
The industry’s political allies understand this threat. They have repeatedly promoted legislation to keep the CFPB away from insurance and to proclaim that state regulators alone are best positioned to protect consumers.
The Mark Walter scandal demonstrates why they are so desperate to preserve that arrangement.
Warren Is Asking What Regulators Should Have Asked Years Ago
Elizabeth Warren’s letter does not prove that Walter, Delaware Life, Clear Spring or any other company committed a crime. Those questions remain for regulators, investigators and courts.
But the letter exposes something broader: the state regulatory system appears to discover major insurance risks only after journalists, whistleblowers, academics or federal prosecutors identify them.
That is not proactive supervision.
It is regulatory cleanup.
I have warned repeatedly that private credit can turn supposedly safe annuities into opaque promises backed by assets that are illiquid, difficult to value and potentially riddled with affiliate conflicts. I have warned that state guaranty associations are not substitutes for the PBGC or FDIC. I have warned that insurers should be required to provide meaningful downgrade protection before retirement savers and pensioners are locked into decades-long contracts.
Warren is now forcing the NAIC to confront those same issues.
Her September 24 response deadline should not produce another polished defense of state regulation, another list of committees or another promise that model rules are “under development.”
Congress should demand the underlying data.
How many insurers have materially misclassified affiliated investments? How much supposedly independent private credit is connected to an insurer’s owner or asset manager? How much exposure has been moved offshore? What happens if several private-credit-heavy insurers require guaranty-association support simultaneously? Which regulators knew about the Walter-related classifications, and when did they know it?
If the NAIC cannot provide convincing answers, Congress should stop pretending that fifty-state regulation is adequate for trillion-dollar national and global insurance complexes.
Elizabeth Warren may currently be the insurance industry’s only serious watchdog in Washington.
The next step is giving a federal watchdog the teeth to do something before the time bomb explodes.
 The CommonSense 401k Project
