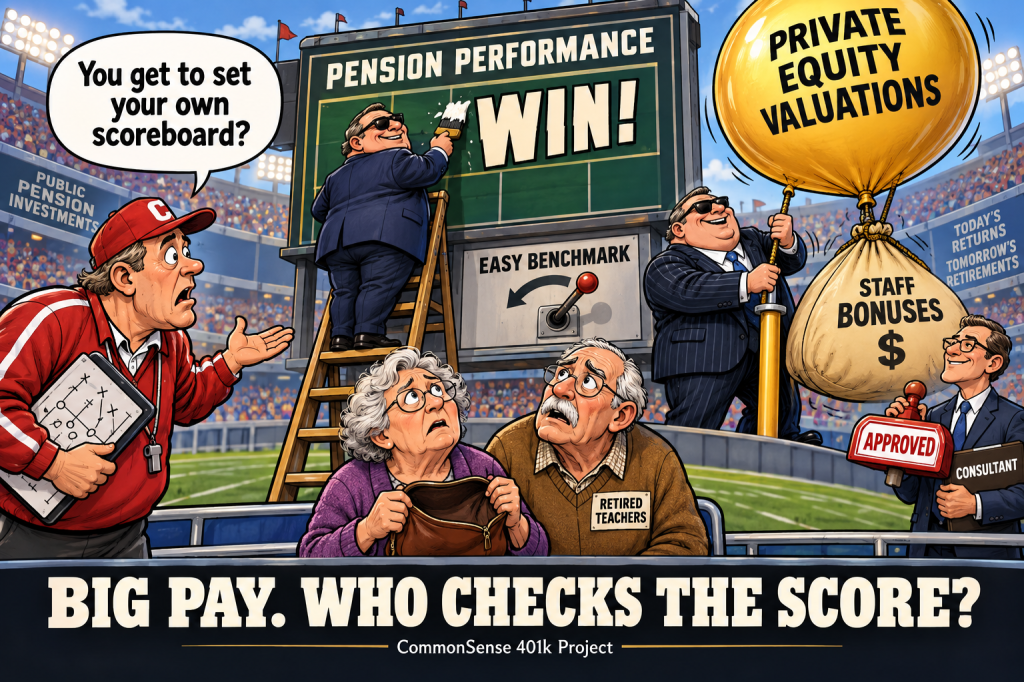
By Christopher B. Tobe | CommonSense 401k Project | October 1, 2026
Public pension executives have joined the ranks of government employees receiving seven-figure compensation. At CalPERS, the chief investment officer collected more than $2.26 million. At Texas Teachers, public-records reporting identified 22 employees receiving at least $1 million in 2024. Wisconsin’s investment board had eight employees above $1 million in its 2025 payroll records.
The biggest college football coaches still earn far more. But public pension staff have entered the compensation territory occupied by many university coaches—and their performance is much harder for the public to judge.
A football coach cannot quietly replace a loss with an appraisal of what the team might have been worth. Pension investment performance, especially where private equity is involved, depends on valuation judgments, reporting conventions and benchmarks that ordinary beneficiaries cannot readily reproduce.
When those same numbers help determine employee bonuses, the people overseeing the investments have a financial interest in the scoreboard.
Millions in pay and a growing national pattern
| Pension organization | Documented compensation finding |
| CalPERS | CIO Stephen Gilmore received $2,260,469 for FY2024–25, including $1,541,719 in annual incentive pay. |
| CalPERS | CEO Marcie Frost who was hired without even a college degree received a $1.15 million incentive award in September 2026, putting her package above $1.7 million when combined with base salary. |
| Texas TRS | CIO Jase Auby received nearly $2.2 million in 2024; 21 other employees also received at least $1 million. |
| Wisconsin Investment Board | Eight employees exceeded $1 million in reported 2025 pay; executive director/CIO Edwin Denson received approximately $1.90 million. |
| Washington State Investment Board | CEO Allyson Tucker received $725,600 and CIO Christopher Hanak $677,900 in reported 2024 earnings. |
These are different reporting periods and compensation measures, rather than a single national ranking. Texas’s unusually large 2024 payout included previously withheld awards. That distinction matters, but it does not erase the scale of the compensation.
Sources: CalPERS compensation analysis and disclosure references, CalMatters on Frost’s September 2026 award, Texas public-records reporting, Wisconsin payroll records, Washington CEO records, Washington CIO records, and Kentucky salary records.
Ohio STRS and the favorable performance number
The most pointed evidence comes from Allen Mendenhall and Dan Sutter’s 2026 paper, Retirement at Risk: The Political Economy of Public Pension Governance.
For 2003–2022, the researchers found that Ohio STRS’s reported investment return exceeded the return they reconstructed from audited financial information in 19 of 20 years. The average difference was approximately 0.33 percentage points annually. They connect the reported measure to investment-staff incentive compensation.
Their estimated $9.3 billion compounded discrepancy is not a finding that employees received $9.3 billion in improper bonuses. It measures the cumulative difference under their calculation.
The paper raises a serious governance question. It does not independently prove intentional falsification or show that private-equity marks caused the entire gap. Differences in cash-flow timing, valuation dates and methodology can systematically affect comparisons; the two return measures must be reconciled before treating the discrepancy as established fraud.
But beneficiaries should not have to take the investment department’s preferred number on faith when that number helps determine its pay.
CommonSense’s July analysis and August follow-up argued that STRS’s reliance on GIPS compliance and performance verification did not resolve the underlying discrepancy. The appropriate answer is a public, independently reviewed reconciliation.
Source: Mendenhall and Sutter’s paper.
Private equity makes the scoreboard harder to check
Publicly traded securities have observable prices. Private-equity interests generally depend on periodic fair-value estimates, often supplied by the managers running the partnerships. Those estimates can be reasonable and still differ materially from the proceeds available in an actual sale.
A valuation increase can therefore contribute to reported pension performance before the pension receives cash from an exit. If that reported performance triggers employee bonuses, staff can be rewarded before the underlying economic result is realized.
Lagged valuations and appraisal-based benchmarks add further complications. They can postpone recognition of market changes and make returns appear smoother. Their effects vary with market conditions; they do not automatically inflate every return.
The incentive problem remains: staff paid for reported outperformance have a personal stake in the valuations and measuring rules. Boards should place those decisions under independent oversight, especially when subsequent write-downs may arrive after bonuses have been paid.
The consultant helps set the pay scale
CommonSense’s September article on Global Governance Advisors examined GGA’s work involving CalPERS and STRS Ohio and its identification of OMERS Ventures among its clients.
The broader concern applies to compensation consulting throughout the industry. Selecting highly paid peers can justify a larger compensation opportunity. Other pensions can then use that newly enlarged package in their own comparisons.
Washington’s official budget materials explicitly describe increases intended to bring investment salary ranges up to peer averages. Florida SBA’s 2025 compensation discussions compared its incentive opportunities with California’s and involved a Mercer benchmarking study.
Those records show how the upward pressure travels. They do not prove that consultants falsified investment returns. They show why trustees must scrutinize both the performance benchmark used to earn a bonus and the compensation benchmark used to enlarge it.
Sources: Washington budget explanation and Florida SBA meeting materials.
Boards must make the bonus calculation reproducible
Pension systems argue that competitive compensation attracts talent and that internal investment management can cost less than outside managers. That argument deserves a fair test: independently measured net returns, appropriate risk comparisons and documented savings.
It cannot be settled by pointing to a high return in a rising market, an easy policy benchmark or another pension’s larger paycheck.
Before approving extraordinary incentive compensation, trustees should require:
- Public reconciliation of the return used for bonuses with audited financial information.
- Long-term performance after all investment costs, compared with transparent, investable alternatives.
- Independent review of private-asset valuations and every material benchmark change.
- Meaningful deferral and clawbacks when later valuations or realized exits undermine the results that generated bonuses.
- Disclosure of compensation peer groups, by location like Columbus and Sacremento consultant relationships and each employee’s actual incentive payments.
Public pension staff manage workers’ deferred wages. When they seek compensation approaching the pay of university coaches, beneficiaries deserve a scoreboard they can verify—and a board willing to challenge the people being paid by it.
CalPERS: sets its own Excessive Pay – off the Charts

