How Wall Street Turned Life Insurance Into a Private Equity Profit Machine — And My Three Bills to Stop It
By Chris Tobe, CFA, CAIA | Commonsense 401(k) Project | November 18, 2026
At The Capitol Forum’s Life & Annuity Industry at a Crossroads conference, I explained why private equity was attracted to the insurance industry: enormous hidden fee spreads, weak state regulation, and retirement assets that investors cannot easily scrutinize. I also outlined three federal bills designed to bring transparency and accountability to this system.
I Went to Washington With a Simple Message: Follow the Fees
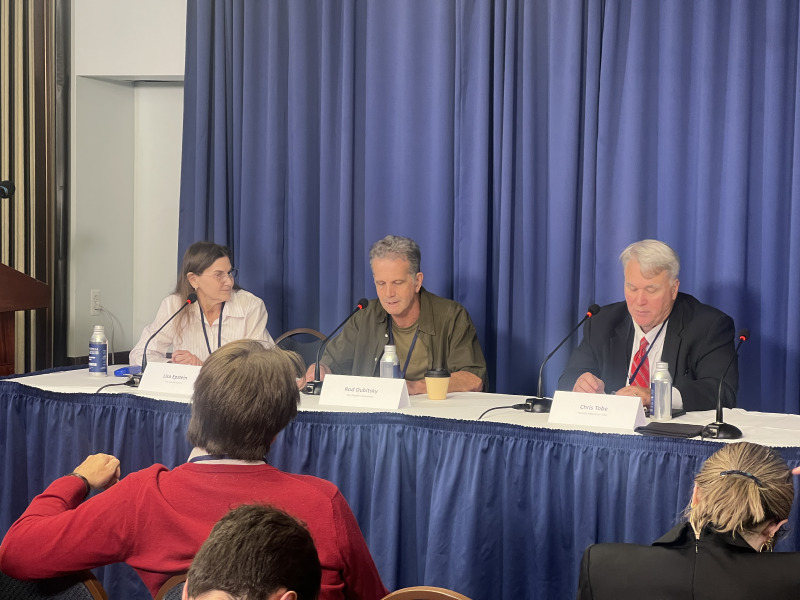
At The Capitol Forum’s November 12 conference in Washington, D.C., I participated in the panel “Asset Side: Private Credit and the Blending of Insurance and Alternative Asset Management,” moderated by Lisa Epstein, alongside Rod Dubitsky and other financial industry specialists. https://thecapitolforum.com/resource/asset-side-private-credit-and-the-blending-of-insurance-and-alternative-asset-management-the-life-annuity-industry-at-a-crossroads/
While much of the insurance debate focuses on credit ratings, private credit valuations, and capital requirements, I wanted to bring a different perspective.
After seven years as an officer at at Transamerica insurance companies, and years investigating pension investments and serving as an ERISA litigation expert, I believe the best way to understand the transformation of the insurance industry is to follow the money.
As I told the panel:
“Yeah, I want to talk about fees a lot. I mean, that’s the one thing I do know about.”
And later:
“It’s all about the fees to me.”
These statements capture what I believe is missing from much of the debate over private equity and life insurance.
The investment risks are real. But the economic incentives driving those risks deserve equal attention.
From 20 Basis Points in Mutual Fund Litigation to 200 Basis Points in Annuity Spreads
One of my central points was the extraordinary difference between fees in SEC-regulated mutual funds and the embedded spreads in insurance contracts.
As I explained:
“We are having mutual fund litigation over a mutual fund that has one share class that charges 40 basis points in fees, and then another that costs 20 basis points in fees. There’s a 20 basis point difference in there. When we get into annuity products, we wouldn’t touch anything that we didn’t make a 200 basis point spread on.”
That statement reflects my experience inside the insurance industry.
In mutual fund litigation, a difference of 20 basis points can generate substantial fiduciary scrutiny.
Yet fixed annuity contracts can involve embedded profit spreads of 200 basis points or more, without the same transparent expense reporting that participants receive for registered mutual funds.
A 200-basis-point spread is ten times a 20-basis-point fee differential.
While insurers will say it includes guarantees, capital, expenses, and risk, they will not break them out because they are typically less than 20bps. So a more accurate statement would be 220bps in spread and 200 bps in profits.
For a $100 million retirement plan investment, 200 basis points represents $2 million annually before considering how the insurer allocates that spread.
Who receives that money? How much compensates the insurer for legitimate risks? How much is retained as profit? How much goes to affiliated asset managers?
Retirement participants deserve answers.
What I Learned Inside Transamerica: Iowa Was No Accident
Perhaps my most revealing comments concerned how insurers historically selected the states in which they issued annuity contracts.
I spent seven years at Transamerica/AEGON, serving as an officer of multiple insurance companies, including Transamerica of Iowa, Transamerica of New York, and Peoples of Iowa.
At the panel, I explained:
“We’d always choose Iowa because they had lower capital requirements and looser regulations.”
I continued:
“It didn’t matter if the 401(k) plan was in California or New York.”
This was my firsthand account of regulatory arbitrage within the state-based insurance system.
The state where an insurance contract is issued or where the insurer is domiciled can have important consequences for regulatory supervision, capital requirements, and permissible investments.
The regulatory differences I observed during my years at Transamerica illustrate why Congress should examine whether today’s state-based system is adequate for large national insurers with complex investment and reinsurance arrangements.
I also explained how attractive the economics could be:
“Some of the other parts of the smaller plans make it three, 400 basis points in fees.”
Then I connected those economics to the expansion of private equity into life insurance:
“This is what attracted private equity to the annuity business.”
The industry’s embedded fee streams were already attractive before private equity firms developed more elaborate combinations of insurance, private credit origination, asset management, and reinsurance.
Private equity did not invent these economic incentives.
It recognized an opportunity to expand them.
Private Equity Found a Magnet: Fee Streams and Weak Regulation
At the panel, I described how the combination of attractive cash flows from spreads and state insurance regulation helped draw private equity firms into the annuity industry.
“It’s that fee stream … and the loose state regulations. All these things just was like a … magnet for private equity to come in.”
This is an important distinction.
Private equity firms such as Apollo have expanded into insurance through business models that combine long-term insurance liabilities with alternative asset management.
An insurer can invest premiums in private credit while affiliated managers may earn origination, servicing, management, or other fees.
The important questions are whether investments are prudently valued, whether related-party fees are reasonable, and whether policyholders and retirees are adequately protected against losses.
I also raised research concerning substantial private equity costs, including estimates of hundreds of basis points in expenses and fees.
These costs and fees vary substantially across funds or strategies. They demonstrate why Congress needs standardized disclosure of total investment costs, including expenses embedded below the fund or insurance contract level.
The public should not have to reconstruct the economics of a retirement product from incomplete filings, complicated contracts, and affiliated-party disclosures.
Thousands of Large 401(k) Plans Hold Fixed Annuities
Another major part of my remarks concerned the scale of fixed annuity exposure in American retirement plans.
I told the panel:
“I have found of the 8,000 largest 401(k) plans … 3,000 of them have fixed annuities.”
This was my estimate based on my research looking at over 5,000 5500s.
I emphasized that these were less than 1% lifetime income annuities.
95% were fixed investment contracts used as principal-preservation or stable value options inside 401(k) plans. Other 4% were various separate account and index products and variable annuities
As I explained:
“These are not lifetime annuities.”
I described my litigation work examining annuities crediting participants 2%–3% while other fixed-income or annuity alternatives were offering substantially higher yields of 4% to 5%.
The Prohibited Transaction Question
I also discussed a more fundamental legal concern.
When an ERISA retirement plan purchases a general account annuity from a service provider or another party in interest, the transaction may raise prohibited transaction issues under ERISA.
As I explained:
“Because of this high risk … all of these annuities and the single annuity credit risk is a prohibited transaction under ERISA.”
That was my legal position opinion and theory, and courts have not at least yet ruled any general account annuities prohibited.
ERISA provides statutory exemptions and the Department of Labor has granted administrative exemptions under specified conditions.
The legal questions include whether a particular transaction falls within a prohibition, whether an exemption applies, and whether its conditions have been satisfied.
I believe those questions deserve far greater attention, especially when a retirement plan’s recordkeeper or affiliated insurer benefits economically from the selection of proprietary annuity products.
My research comparing concentrated general account insurance exposure with diversified synthetic stable value arrangements reinforces the importance of examining these conflicts.
The Political Problem: Who Regulates the Regulators?
I also raised the political influence of private equity and other financial interests.
My public pension investigations, including work involving CalPERS, have examined opaque investment arrangements, consultant conflicts, fees, and governance failures.
At the panel, I warned about the influence of political fundraising and dark money on public pension oversight and state insurance regulation.
It is that a system relying on dozens of state regulatory authorities may be vulnerable to inconsistent standards, political pressure, and competition to attract insurance business.
My experience with insurance domicile decisions illustrates why this concern deserves investigation.
Congress should require greater disclosure of political contributions, regulatory conflicts, and related-party financial relationships, while preserving the independence of legitimate state regulatory functions.
I Announced Three Proposed Federal Bills
The most important part of my participation was not simply identifying problems.
I explained that I had already begun working with congressional staff on legislative solutions.
As I told the panel:
“I’ve already given some proposed bills out there.”
I referred to my communications with staff associated with Senator Elizabeth Warren and Senator Bernie Sanders’ HELP Committee.
I then described three proposals designed to address the risks of opaque retirement investments and insurance products.
Bill One: Federal Life Insurance Oversight Act
My first proposal would establish a meaningful federal consumer protection role over life insurance and annuities, coordinated with existing state regulators.
I told the panel:
“The first one … it’s simply this: Consumer Financial Protection Bureau, CFPB, put it over the 50 state insurance commissions simply as a start.”
The legislative concept is straightforward, although implementing it would require Congress to address existing federal restrictions on CFPB insurance authority and the division of responsibilities between federal and state regulators.
The proposed legislation would strengthen oversight of private credit investments, offshore reinsurance, affiliated investment managers, valuation practices, capital adequacy, and policyholder protections.
The goal is not to abolish state insurance regulation.
It is to ensure that the increasingly national and international life insurance business receives coordinated federal scrutiny.
Bill Two: Pension Risk Transfer Annuity Participant Protection Act
My second proposal addresses the movement of pension obligations from diversified defined benefit pension trusts to insurance companies.
I explained:
“It’s mostly about transparency and disclosure of the underlying fees and profits made in that annuity.”
Pension risk transfers can reduce corporate pension liabilities, but retirees should not lose important protections without meaningful disclosure and enforceable safeguards.
My proposal would require more transparent insurer selection, disclosure of investment risks and transaction economics, stronger downgrade protections, and mechanisms for restoring or supplementing PBGC-backed protection under specified circumstances.
The objective is to protect retirees throughout the life of the annuity, not merely at the moment the pension transfer occurs.
Bill Three: 401(k) Private Equity Transparency Act
My third proposal is the most comprehensive.
At the conference, I explained:
“My third bill … creates disclosures, not on annuities, but also on private equity, private credit and crypto.”
The proposal would expand disclosure requirements for opaque retirement investments, including collective investment trusts, target-date funds, private equity, private credit, and annuity contracts.
A central feature would be expanded Form 5500 reporting.
As I told the panel:
“It would require … a much higher level of transparency on all the contract investments.”
This includes underlying holdings, investment fees, related-party compensation, valuation assumptions, liquidity restrictions, and other information necessary for fiduciaries and participants to understand their investments.
The proposal also addresses inconsistent valuation practices, particularly when private assets are combined with publicly traded securities inside target-date funds.
Congress should not permit an investment to avoid meaningful disclosure simply because it is packaged as a contract rather than a registered security.
Even Partial Legislation Would Be a Beginning
I recognize that major financial reform legislation is difficult to enact.
At the conference, I acknowledged that creating federal insurance oversight would not be easy.
But I believe the legislative process must begin.
As I explained:
“Even if it’s partial, I wanted to start that process with those two committees.”
That statement captures my current priority.
My goal is to move the debate beyond general warnings about private credit and toward concrete legislation that congressional staff can evaluate, amend, and advance.
The insurance industry has become increasingly intertwined with private equity, private credit, offshore reinsurance, and alternative asset management.
Yet retirement participants and annuity holders still lack access to much of the information needed to evaluate the economic arrangements supporting their investments.
The Bottom Line: Follow the Fees, Disclose the Risks, Protect Retirees
The Capitol Forum deserves credit for convening an important discussion about the future of the life insurance industry.
My contribution was to connect the financial risks to the underlying economic incentives and to practical legislative reforms.
I have worked inside insurance companies. I have investigated public pension investments. I have examined retirement plan annuity contracts through litigation.
Those experiences have led me to one central conclusion:
The enormous fee opportunities in opaque insurance and private market products help explain why Wall Street is so determined to expand them.
The solution is to require transparent fees, independently supportable valuations, enforceable fiduciary standards, and meaningful consumer protection.
That is the purpose of my three proposed bills.
As I told the panel, my initiative is to push transparency forward:
“From the end user point of view.”
The end users are the workers and retirees whose money supports this entire financial system.
It is time for Congress to put them first.
Chris Tobe, CFA, CAIA, is Chief Investment Officer of Hackett Robertson Tobe, a pension investment consultant, author, and ERISA expert witness. He previously served as an officer of multiple Transamerica/AEGON insurance companies and publishes the Commonsense 401(k) Project.
Watch the panel: The Capitol Forum — Asset Side: Private Credit and the Blending of Insurance and Alternative Asset Management
Related Commonsense research:

