How Private Equity Will Sneak Into Your Retirement Account
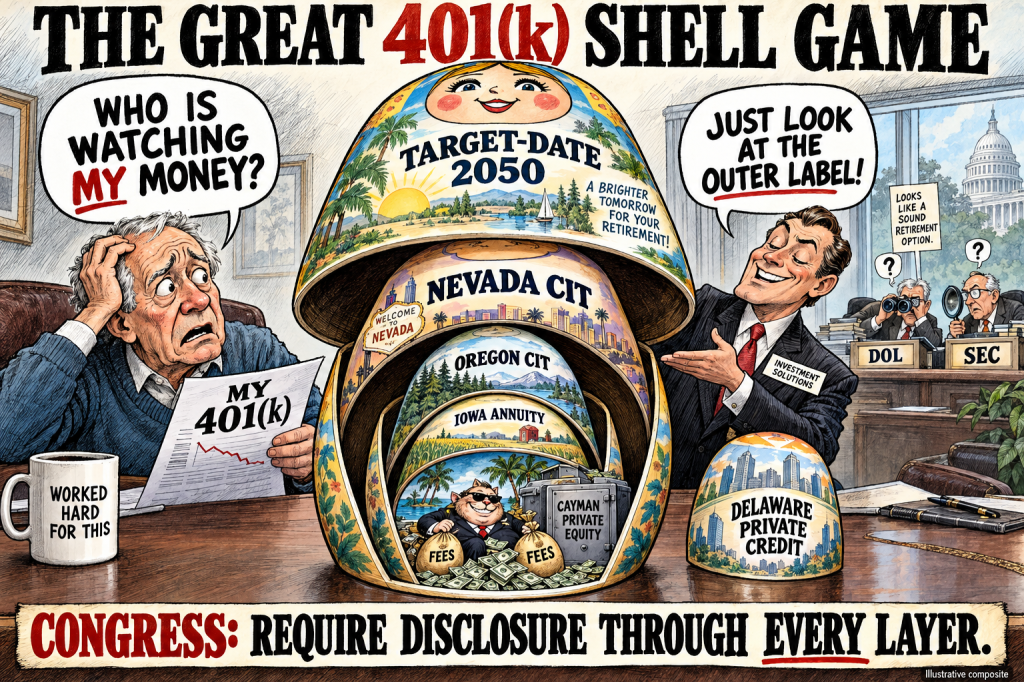
Private equity wants access to your 401(k). The easiest route is to bury its contracts inside an investment with a reassuring name: a target-date fund.
Private equity contracts can impose fees and expenses 20 times those of low-cost 401(k) investments. A 2% annual management fee alone is 20 times a 0.10% fund expense ratio—before carried interest and additional expenses. Managers also exercise enormous discretion over valuations used to calculate their reported performance.
My position is straightforward: no competent, honest, transparent regulatory system should permit retirement investments to hide their full costs or let managers mark their own performance scorecards without rigorous, independent scrutiny.
The industry wants access to workers’ retirement savings without accepting the transparency and accountability associated with SEC-registered mutual funds. Collective investment trusts, or CITs, provide a route around that mutual-fund framework.
Your retirement account can remain subject to ERISA while the investments inside it move through a maze of different regulatory systems.
The Department of Labor oversees ERISA fiduciary obligations. The SEC regulates registered mutual funds. State and Federal Banking regulators supervise CIT trustees. State insurance departments regulate annuity issuers. Private funds add another layer of legal entities, contracts, exemptions, and sometimes offshore domiciles.
Each layer gives the industry another opportunity to obscure who holds the money, who sets the fees, who values the assets, and who is responsible when something goes wrong.
The Target-Date Doorway
Target-date funds are a powerful distribution channel because employers frequently select them as the plan’s default investment, known as a qualified default investment alternative, or QDIA. Workers can end up in these products without making an affirmative investment selection.
Historically, a target-date portfolio generally combined stock and bond funds, changing their proportions as the retirement date approached. The industry’s ambition is to add private equity, private credit, annuities, and other lucrative contracts to that mix.
The investment wrapper is already changing. Mutual funds were 71% of target date funds in 2015. By the end of 2025, CITs held 54% of target-date assets, leaving mutual funds with approximately 46%. CITs have become the majority vehicle in the target-date market.
CITs are exempt from the registration framework that applies to mutual funds. Most CIT trustees are state-chartered trustees with weak oversight and controls.
Follow the Money laundered by layers of Weak Regulators
Consider a plan offering five target-date funds: 2030, 2040, 2050, 2060, and 2070. Each uses a different allocation among six underlying investments.
The outer target-date vehicle is a CIT administered by a Nevada-chartered trust company. Inside it, the money travels through additional layers:
| Underlying investment | Intermediate vehicle | Contract or investment inside it |
| Large-cap equity | Oregon-chartered trustee’s CIT | S&P 500 index exposure through a separate-account annuity issued by an Iowa-domiciled insurer |
| Small-cap equity | Pennsylvania-chartered trustee’s CIT | Small-cap index exposure through a separate-account annuity issued by a Connecticut-domiciled insurer |
| International equity | Oregon-chartered trustee’s CIT | International index exposure through a separate-account annuity issued by a Kansas-domiciled insurer |
| Fixed income | Oregon-chartered trustee’s CIT | General-account fixed annuity issued by an Iowa-domiciled insurer |
| Private credit | Nevada-chartered trustee’s CIT | Interest in a Delaware-domiciled private credit fund |
| Private equity | Nevada-chartered trustee’s CIT | Interest in a Cayman Islands-domiciled private equity fund |
This is an illustrative composite based on structures I have encountered or seen in development. It is not a claim that one identified plan currently holds this exact combination.
The insurer’s domiciliary state identifies its primary insurance regulator. A private fund’s Delaware or Cayman domicile identifies where the entity is organized; it does not, by itself, establish who regulates its investment manager or what investor protections apply.
That is precisely why Congress must require both domicile and actual regulatory jurisdiction to be disclosed.
A worker may think “large-cap equity” means ownership of a conventional stock fund. In this example, the worker’s exposure runs through a CIT and an insurance contract. The words “private equity” reveal even less about the underlying partnership agreement, valuation practices, fee arrangements, leverage, and withdrawal restrictions.
A single target-date label can conceal a chain of contracts spanning several states and an offshore jurisdiction.
Disclosure Must Reach the Underlying Contracts
Existing disclosures do not give participants a uniform, comprehensive map through every layer of a multi-asset retirement investment.
Workers need to know more than the outer fund’s name, allocation, and reported expense ratio. They need to know:
- What legal entities and contracts actually hold their retirement money.
- Which regulator supervises each trustee, insurer, fund, and investment manager—and which activities that supervision covers.
- Every layer of fees, expenses, carried interest, insurance spreads, and payments to affiliates or service providers.
- Who values the investments, how performance is calculated, and whether reported returns receive independent verification.
- What happens when participants want their money back, an insurer is downgraded, or a private fund suspends withdrawals.
A regulator overseeing the trustee is not necessarily examining every underlying contract for the protections workers assume they have.
Congress should prohibit the use of regulatory layering to conceal information that would have to be disclosed if the plan held the underlying investment directly.
Congress Must Act Regardless of Intel
The Supreme Court’s Anderson v. Intel case concerns whether an investment-underperformance claim must identify a “meaningful benchmark” to survive the pleading stage. That decision could affect whether participants reach discovery and obtain evidence about complicated investment arrangements. It does not directly decide a comprehensive statutory right to underlying-investment disclosure.
Large plans can use master trusts and custom portfolios to create similar layers of complexity. Congress must cover those structures alongside CITs and mutual funds.
Workers should not have to file a lawsuit, defeat a motion to dismiss, and spend years pursuing discovery to learn where their retirement money went.
Transparency must be a statutory obligation that applies before the money is invested.
Congress should require a standardized Underlying Investment and Regulatory Disclosure Schedule attached to Form 5500 and available to participants without charge. It should cover every target-date fund, CIT, master trust, separate account, and other pooled or multi-asset arrangement used by an ERISA plan.
The schedule should require:
- Complete identification of every underlying fund and investment contract, through every intermediate layer, including its legal name, structure, domicile, and share of plan assets.
- Identification of every responsible regulator, the entity and activity it supervises, and applicable registration exemptions. “SEC-registered adviser” must never substitute for disclosure that the fund itself is unregistered.
- Full disclosure of costs at every level, in dollars and percentages, including management fees, carried interest, fund expenses, underlying portfolio-company charges, insurance spreads, commissions, and affiliate payments.
- Standardized performance and valuation disclosures, including gross and net returns, valuation methods, independent verification, and whether a fund claims compliance with recognized performance-reporting standards.
- Complete liquidity and credit-risk disclosures, including lockups, gates, surrender charges, market-value adjustments, capital commitments, downgrade provisions, and rights following issuer default.
- Public access to governing investment contracts and material amendments, with no confidentiality clause permitted to override the disclosure obligation.
Trade-secret claims should never conceal fees, valuation methods, withdrawal restrictions, or regulatory jurisdiction from the workers whose savings finance these investments.
The legislative principle is simple: if an investment receives tax-favored retirement money, its managers must disclose what they are selling, what they are charging, how they calculate performance, and who regulates them.
A retirement date on the label is no excuse for secrecy underneath.
Before private equity gets another dollar of workers’ default retirement savings, Congress should require the industry to open the books.

